Anthropic told prospective investors on 14 October that it earned $16.8 billion in revenue in the third quarter of 2026. It also said it earned $1.70 for every dollar it spent on computing power in that quarter. Those two numbers, reported by Reuters, Bloomberg and the Financial Times from people who attended the meeting, are the strongest case yet for an Anthropic IPO. They’re also harder to read than they look.
The difficulty is the third number. A confidential prospectus seen by Reuters in September showed that Anthropic has committed at least $518 billion to computing infrastructure over roughly a decade, and that about 80% of it can’t be cancelled. So the question for anyone weighing the listing isn’t whether revenue is growing. It’s whether revenue per compute dollar can keep rising faster than the bills Anthropic has already signed.
Status as of 18 October 2026: Anthropic has officially confirmed only that it confidentially submitted a draft S-1 on 1 June 2026. It has announced no IPO date, share count or price. A November listing has been reported by the Wall Street Journal and Bloomberg, citing unnamed sources, but it isn’t confirmed. We found no report of a public S-1 on the SEC’s EDGAR database. All financial figures below come from investor-day attendees or a confidential prospectus, not from audited public filings.
Key Takeaways
- Confirmed: Anthropic submitted a confidential draft S-1 on 1 June 2026. It has not announced an IPO date.
- Reported: Quarterly revenue rose from about $4.7 billion in Q1 2026 to $16.8 billion in Q3. Growth slowed from roughly 147% in Q2 to about 45% in Q3.
- Reported: Anthropic said it was profitable on an adjusted basis and cash-flow positive in Q3, but the adjustments haven’t been fully disclosed.
- Our analysis: A $1.70 revenue-to-compute ratio implies compute equal to about 59% of revenue. That can’t sit alongside an 85% gross margin unless most compute, probably training, is booked outside cost of revenue.
- Reported: About 80% of the $518 billion in commitments is non-cancelable or payable regardless of use. Payment schedules haven’t been reported.
- Unresolved: A mid-November listing would need a public S-1 by late October. Whether that happens is the next hard signal.
Quick Navigation
- The numbers behind the Anthropic IPO story
- What the reported compute ratio actually tells us
- The $518 billion question: commitments are not spending
- Where CoreWeave fits into the picture
- What profitability and free cash flow do, and don't, prove
- The Anthropic IPO timeline: confirmed facts and reported expectations
- What to watch before the Anthropic IPO
- Conclusion
- Frequently Asked Questions
- Is Anthropic going public?
- When is Anthropic expected to IPO?
- Has Anthropic filed an S-1?
- How much revenue does Anthropic generate?
- Is Anthropic profitable?
- How much is Anthropic spending on compute?
- What does the $1.70 revenue-per-compute-dollar figure mean?
- What are Anthropic's infrastructure commitments?
The numbers behind the Anthropic IPO story
The quarterly figures come from an investor day at Anthropic’s San Francisco headquarters on 14 October. Reuters cited two attendees, and Bloomberg cited people familiar with the presentation. Anthropic didn’t respond to Reuters’ request for comment and hasn’t published the results. The figures are calendar 2026 quarters. They describe revenue earned in each quarter, not an annualised run rate.
Table: scroll sideways to view all columns when needed.
| Quarter (2026) | Reported revenue | Change on prior quarter (our calculation) | Source and qualification |
|---|---|---|---|
| Q1 | $4.7bn (FT: about $4.8bn) | n/a | Investor-day attendees |
| Q2 | $11.6bn (FT: $11.5bn) | +147% (FT figures: +140%) | Investor-day attendees |
| Q3 | $16.8bn | +45% (FT figures: +46%) | Reuters, Bloomberg and FT all report $16.8bn |
The small differences between outlets matter less than what they agree on. Revenue for the first nine months of 2026 comes to $33.1 billion on either set of figures. That’s about 7.2 times the roughly $4.6 billion Anthropic earned in all of 2025, according to the prospectus Reuters reviewed.
The slowdown is just as clear. Q2 more than doubled Q1, while Q3 added 45%. The Decoder linked the slower quarter to a summer seasonal dip and new competition. Anthropic also told investors that 5% to 7% of revenue came from distillation, meaning rival labs paying to train on Claude’s outputs. Per the FT, as summarised by Simon Willison, it had cut that business back “materially” in Q3. That’s revenue the company is choosing to shrink.
One accounting point affects every ratio that follows. Anthropic records the full value of Claude sales made through cloud partners such as AWS and Google, and books the partners’ share as an expense. OpenAI records only its net share. Axios reported that a source familiar with Anthropic’s finances put the effect of switching to net reporting at about 6% to 10% of revenue. The S-1 should settle the treatment. Until then, comparisons with OpenAI need that caveat.
What the reported compute ratio actually tells us
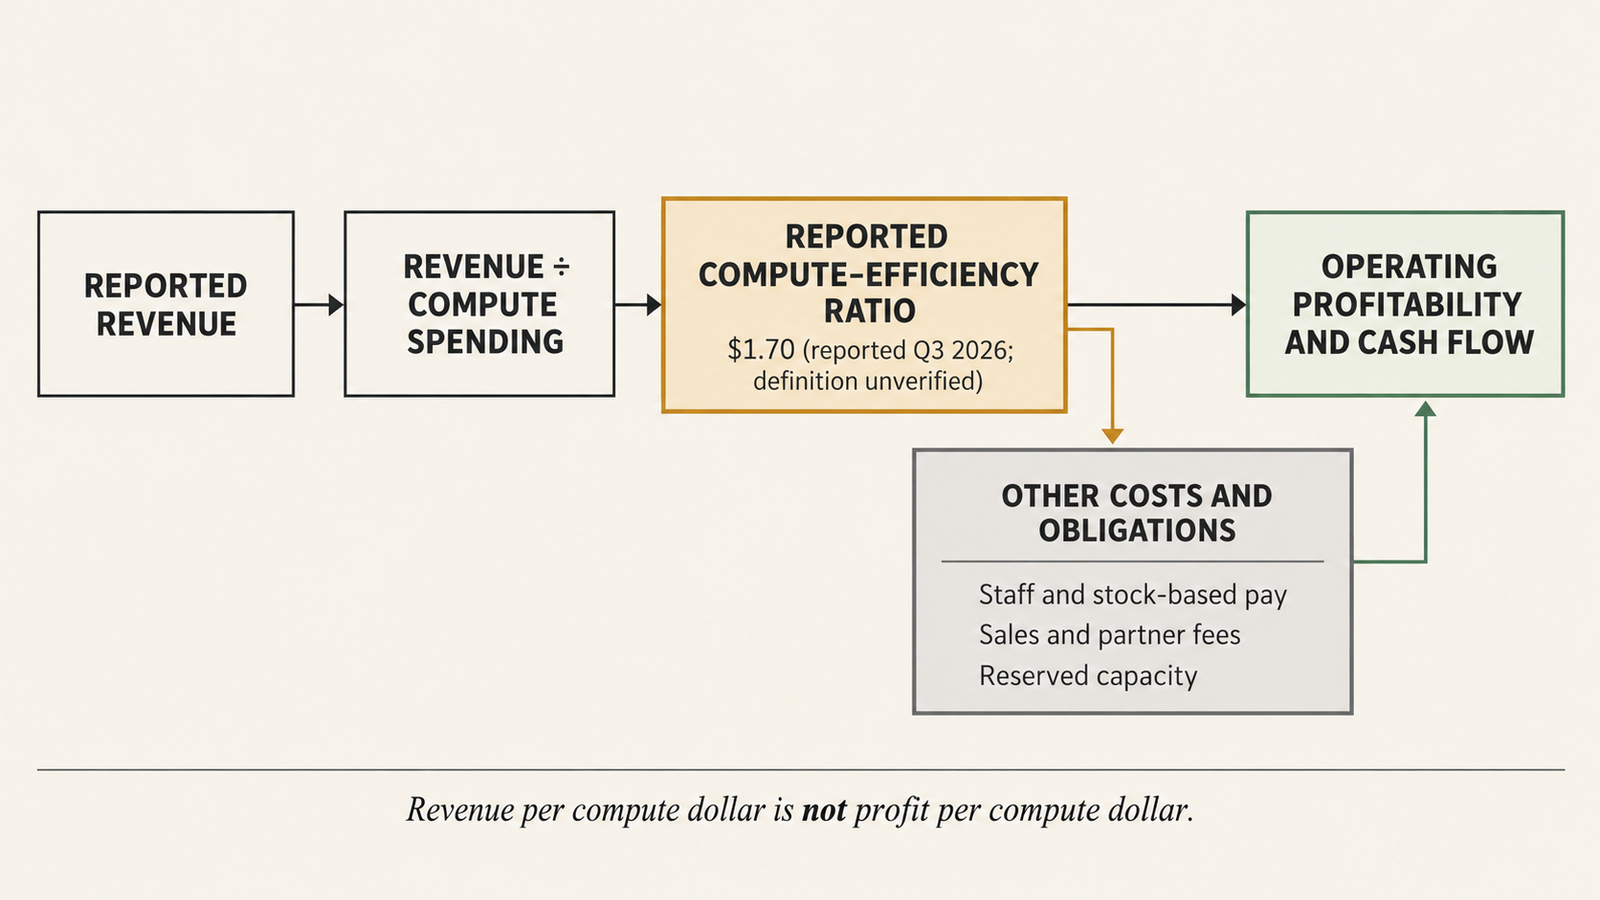
According to the FT’s investor-day reporting, Anthropic earned $1.70 in revenue for every dollar spent on “computing power” in Q3. It’s the most useful number in the story, and the most easily misread.
Start with what it can’t mean. A ratio of 1.70 doesn’t mean Anthropic keeps 70 cents of profit per compute dollar. Revenue also has to pay for staff, sales, cloud-partner fees, offices, legal costs and stock-based compensation. The ratio measures how hard the hardware is working commercially, not how profitable the company is.
If the ratio uses Q3 revenue and Q3 compute spending, the arithmetic is straightforward. These are our calculations, and they depend on that assumption:
Implied Q3 compute spend = $16.8bn ÷ 1.70 ≈ $9.9bn
Compute as a share of revenue = 1 ÷ 1.70 ≈ 59%
2025 equivalent = $4.6bn revenue ÷ $7.33bn compute and infrastructure costs ≈ $0.63
The 2025 figures come from the confidential prospectus as reported by Reuters. On that basis, Anthropic went from earning 63 cents per compute dollar in 2025 to $1.70 in Q3 2026, close to a 2.7-fold improvement. If the definitions match, that’s the clearest evidence in the reporting that the business is scaling. Revenue grew much faster than the hardware bill.
The tension with an 85% gross margin
Now set it beside the 85% gross margin Bloomberg reported. Gross margin is revenue minus cost of revenue, divided by revenue. At 85%, cost of revenue in Q3 would be at most about $2.5 billion. But the ratio implies about $9.9 billion of compute. If all of that compute counted as cost of revenue, the gross margin couldn’t exceed about 41%.
Both numbers can be true only if roughly three-quarters of the compute spend, around $7.4 billion, sits outside cost of revenue. The likeliest home is training, which AI companies often treat as research and development. Earlier reporting cited by BeInCrypto described an 80% gross margin that “left out training costs,” which fits that reading. It hasn’t been confirmed for the 85% figure.
That doesn’t make the gross margin misleading. It means it measures something narrow: the cost of serving models already built. The $1.70 ratio is the broader test, because it appears to count all computing power. To interpret it fully, readers need four things the S-1 should disclose:
- whether “computing power” includes training, inference and research compute together;
- whether it includes payments on reserved but idle capacity;
- whether revenue is gross of cloud-partner fees, which would flatter the ratio (on a 6% to 10% net-basis haircut, $1.70 becomes about $1.53 to $1.60);
- whether the Q3 figure is typical or flattered by timing, such as a training run that hadn’t started.
The $518 billion question: commitments are not spending
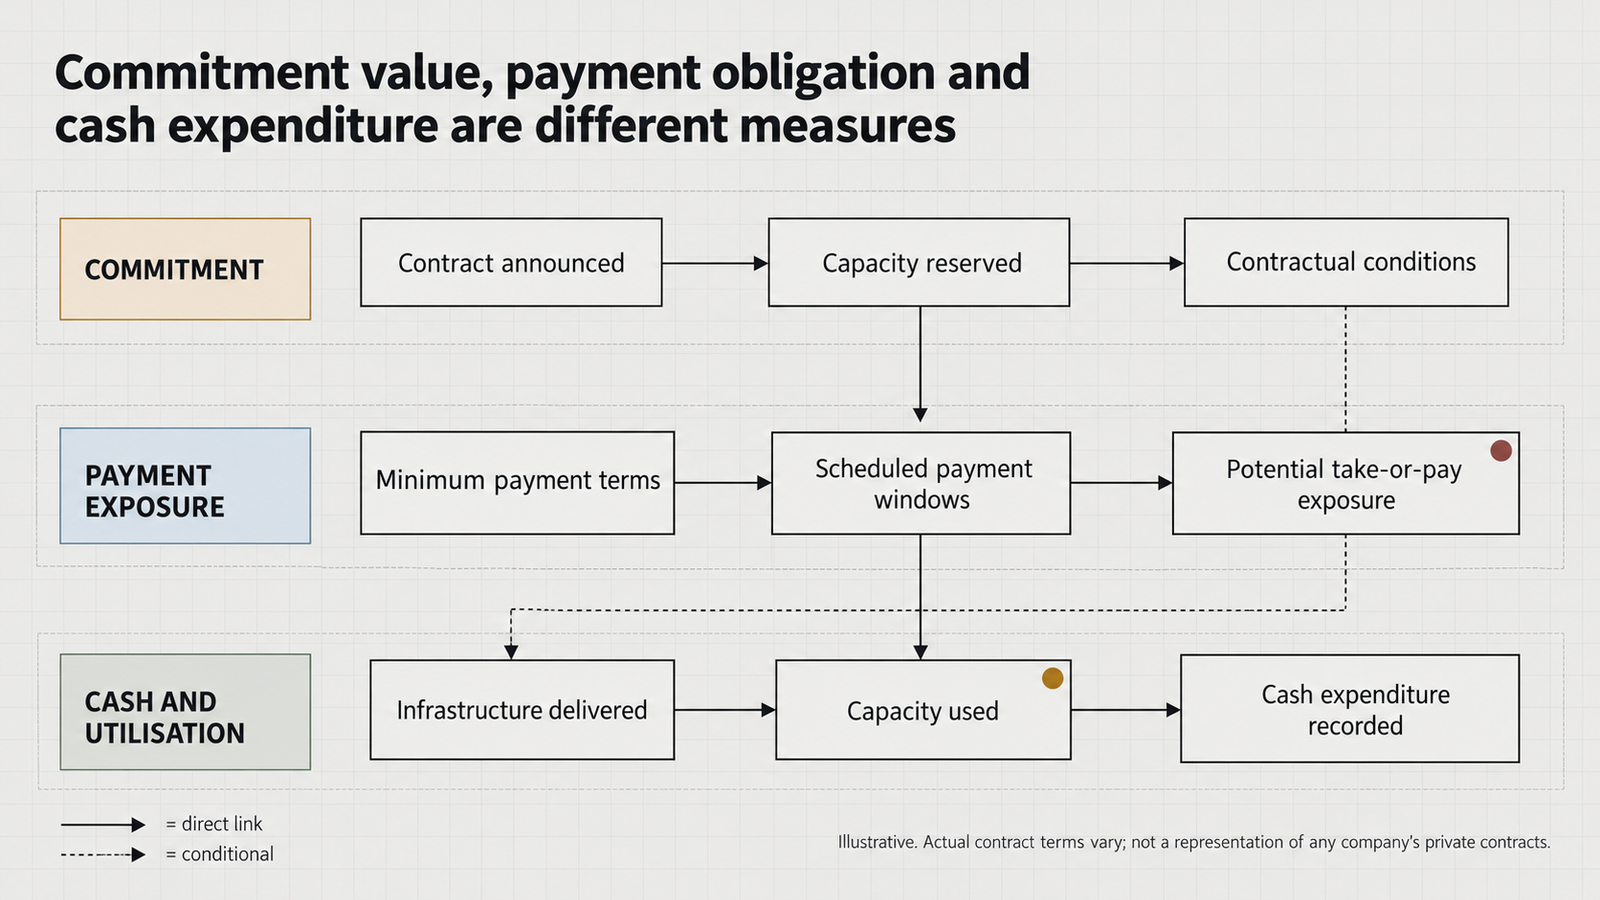
The $518 billion figure comes from the confidential prospectus Reuters reviewed on 29 September. It isn’t debt, and it isn’t money already spent. It’s the total of contracts to buy computing capacity and equipment over roughly a decade. That’s why it doesn’t contradict a cash-positive quarter: the obligations fall due over years, while the quarter’s cash flow covers one quarter’s payments.
Table: scroll sideways to view all columns when needed.
| Counterparty | Reported commitment | Period | Cancelability, as reported |
|---|---|---|---|
| Broadcom (equipment leases) | ~$161.2bn | Includes a five-year, $125.2bn TPU lease | Non-cancelable except on default |
| $111.1bn | Apr 2026 to Jul 2033 | Payable regardless of usage | |
| Amazon | $110bn | May 2026 to Apr 2036 | Payable regardless of usage |
| xAI (Nvidia-based capacity) | Up to $84.5bn | Through 2029 | Largely cancelable with 90 days’ notice |
| Microsoft | $31.4bn | Nov 2026 to May 2033 | Non-cancelable except for Microsoft’s uncured breach |
| AMD | Expected to exceed $20bn | Not reported | AMD also agreed to buy up to $5bn of Anthropic stock |
The first four non-cancelable lines add up to about $414 billion. That matches the prospectus’s statement that about 80% of the total “is non-cancelable or requires payment regardless of usage.” Anthropic’s own wording on Google is blunt: “If our actual spend falls short, we must pay Google the difference.”
That is take-or-pay exposure. If demand falls short of the commitment, Anthropic pays anyway, and the unused capacity drags the revenue-per-compute ratio down. Our earlier analysis of the obligation behind Anthropic’s $518 billion compute commitment goes through each partner’s terms in detail.
What the commitments assume about revenue
A rough scale check helps, as long as it’s treated as an illustration, not a schedule. Spreading each non-cancelable contract evenly over its reported period gives about $56 billion a year. That counts Google over about seven years, Amazon over ten, Microsoft over six and a half, and only the five-year Broadcom TPU lease. Anthropic’s annualised Q3 compute spend, at four times the implied $9.9 billion, is about $40 billion. To keep the ratio at $1.70 against $56 billion a year of compute, annual revenue would need to reach about $95 billion. Q3 annualised is $67 billion.
The real schedules almost certainly aren’t flat. Capacity typically ramps as data centres come online, so early years are lighter. But the illustration shows what the commitments assume: revenue keeps growing well beyond its current pace. A slowdown from 147% to 45% in a quarter is the kind of shift that makes that assumption worth testing.
Where CoreWeave fits into the picture
CoreWeave announced a multi-year agreement with Anthropic on 10 April 2026 to run production Claude workloads. It disclosed no contract value, duration or capacity. CoreWeave isn’t named in the reported six-partner breakdown of the $518 billion, so we can’t tell whether that contract sits inside the total, is too small to list, or is reported elsewhere.
The October “repricing” is a different event. It concerns CoreWeave’s own debt. Its bonds fell far enough that yields reached roughly 15% to 16% on 14 and 15 October, while the fixed coupons stayed the same, as we detailed in our analysis of CoreWeave’s debt repricing. Nothing we found shows any change to CoreWeave’s agreement with Anthropic.
The connection is indirect but real. Lenders are charging more to finance GPU-heavy infrastructure. Anthropic’s largest commitment, the Broadcom TPU lease, is itself funded by a roughly $60 billion debt structure that Bloomberg reported. If the cost of financing AI capacity rises, providers will try to pass it on when contracts renew or expand. That’s a pressure on future compute prices, not evidence about Anthropic’s current terms.
What profitability and free cash flow do, and don’t, prove
Anthropic told investors it was profitable “on an adjusted basis” in Q3. The FT reported it was the second straight such quarter. Bloomberg reported an adjusted operating margin of “over 11%” and positive free cash flow. Free cash flow is operating cash flow minus capital spending.
Each of those claims is narrower than it sounds.
- Adjusted isn’t GAAP. The FT and The Information both reported that the adjusted margin excludes stock-based compensation, which is a real cost even though no cash leaves the company: it dilutes shareholders. Other adjustments haven’t been disclosed. The 2025 comparison shows how far the measures can diverge. On the prospectus figures Reuters reported, Anthropic’s 2025 operating loss was more than $8 billion before liability writedowns. Its net loss was about $42 billion, of which about $34 billion was a non-cash charge on convertible financing.
- The margin’s period is unclear. Bloomberg’s “over 11%” reads as a Q3 figure. The Decoder, citing The Information, described 11% as the margin for the year through Q3. Those are different claims, and the reporting doesn’t settle which is right.
- Cash flow can be front-loaded. Large customers sometimes prepay, and capacity contracts can defer payments until hardware arrives. Either would make a quarter’s cash flow look stronger than the underlying economics. No cash-flow amount has been reported, so there’s no way to tell. Anthropic ended 2025 with $20.28 billion in cash, according to the prospectus as reported, and it isn’t short of money. The IPO is about funding commitments that grow faster than current cash generation.
What the reported margins add up to
The useful reading is this. If 11% adjusted operating margin and $1.70 per compute dollar both describe Q3, compute took about 59% of revenue. Everything else before stock-based pay took about 30%, leaving roughly $1.8 billion of adjusted operating profit. That’s a real business at real scale. It’s also thin enough that a few points of compute cost or a quarter of idle capacity would erase it.
The Anthropic IPO timeline: confirmed facts and reported expectations
Table: scroll sideways to view all columns when needed.
| Date (2026) | Event | Status |
|---|---|---|
| 1 June | Anthropic confidentially submits a draft S-1; shares and price not set | Official |
| 18 September | WSJ reports a November IPO plan, per PYMNTS | Anonymous sources |
| 29 September | Reuters reports the confidential prospectus: $518bn of commitments, 2025 results | Document seen by Reuters, not public |
| 1 October | Bloomberg: listing as soon as mid-November; marketing could start the week of 9 November, per Yahoo Finance | Anonymous sources; plans “remain fluid” |
| 4 October | No public S-1 on EDGAR, 126 days after the confidential submission | Secondary check |
| 14 October | Investor day in San Francisco; Q3 figures shared | Reported by attendees |
| 15 October | Reuters: some investors weigh a valuation near $1.5 trillion, below the roughly $2 trillion earlier expected | Anonymous sources |
The November timeline is unconfirmed. Anthropic hasn’t announced it, and Bloomberg itself said the dates could change.
There is a mechanical test, though. A company that files confidentially must make its registration statement public at least 15 days before it starts a roadshow, as Yahoo Finance noted. Marketing in the week of 9 November would therefore need a public S-1 by about 25 October. We couldn’t query EDGAR directly for this article, and we found no report of a public filing as of 18 October. That isn’t proof that nothing has been filed confidentially since. Amended drafts can be submitted privately too.
What to watch before the Anthropic IPO
- A public S-1 on EDGAR. It would turn reported figures into audited ones, and its timing confirms or kills the November window.
- The definition of compute cost. The S-1’s segment and cost disclosures should show whether training sits in cost of revenue or R&D. That decides whether 85% gross margin and $1.70 per compute dollar describe the same business.
- The commitment schedule. The contractual obligations table would show how much of the $518 billion falls due each year. Back-loaded payments buy time; front-loaded payments test revenue growth sooner.
- Q4 growth and distillation. Anthropic reportedly told investors that lower distillation revenue will weigh on the current quarter. A further slowdown would sharpen the commitments question.
- Gross versus net revenue. If the SEC pushes for net reporting of cloud-partner sales, every ratio here moves down by a similar amount.
- Stock-based compensation. Its size determines the gap between adjusted and GAAP operating profit.
Conclusion
The reported numbers support one conclusion. Anthropic has turned compute into revenue far more efficiently in 2026 than in 2025, and on an adjusted basis that is now enough to cover its other costs.
They don’t yet show that the efficiency will hold against $414 billion of commitments that must be paid whether or not the demand arrives. That depends on two disclosures only a public S-1 can provide: what “computing power” includes, and when the commitment payments fall due. Until those appear, the $1.70 ratio is the right number to watch and the wrong number to treat as settled.
Frequently Asked Questions
Is Anthropic going public?
It is preparing to. Anthropic confidentially submitted a draft S-1 on 1 June 2026, which gives it the option to list after SEC review. It hasn’t announced an IPO date or terms.
When is Anthropic expected to IPO?
Bloomberg and the Wall Street Journal reported a November 2026 target, with trading possibly before Thanksgiving. Both cited unnamed sources, and Anthropic hasn’t confirmed the timing.
Has Anthropic filed an S-1?
Only confidentially, on 1 June 2026. Reuters has reported on a prospectus it saw, but no public S-1 had appeared on EDGAR in the reporting we found as of 18 October 2026. Our explainer on what the Anthropic S-1 must disclose covers how that filing process works.
How much revenue does Anthropic generate?
Investor-day attendees reported $16.8 billion for Q3 2026 and about $33.1 billion for the first nine months. These figures aren’t audited or published by Anthropic.
Is Anthropic profitable?
On an adjusted basis, reportedly yes, for Q2 and Q3 2026. The adjustments exclude stock-based compensation at least. In 2025, it reported a large operating loss and a net loss of about $42 billion, according to the prospectus Reuters saw.
How much is Anthropic spending on compute?
Reported 2025 compute and infrastructure costs were $7.33 billion. No Q3 figure has been reported, but the $1.70 ratio implies about $9.9 billion if it uses same-quarter figures. That’s our calculation, not a disclosed number.
What does the $1.70 revenue-per-compute-dollar figure mean?
It reportedly means Q3 revenue was 1.7 times compute spending. It measures revenue efficiency, not profit, because staff, sales and other costs also come out of revenue.
What are Anthropic’s infrastructure commitments?
At least $518 billion over about a decade with six partners, per the confidential prospectus Reuters saw. About 80% is non-cancelable or payable regardless of usage. These are future obligations, not current spending or debt.
Keep reading
Here are the latest posts from the blog.
Agentic AI Security: What Changes When the Model Can Act
Anthropic IPO: Revenue, Compute Costs and the November Timeline
Agentic AI vs Generative AI: Cost, Risk and Control