Anthropic IPO: The $895 Billion Question Behind Its Valuation

Anthropic IPO valuation

Last updated: 9 November 2026. Latest confirmed development: Anthropic’s amended S-1, filed on 2 November, still leaves the share count and the IPO price range blank. As of our research on 9 November, we found no later amendment.

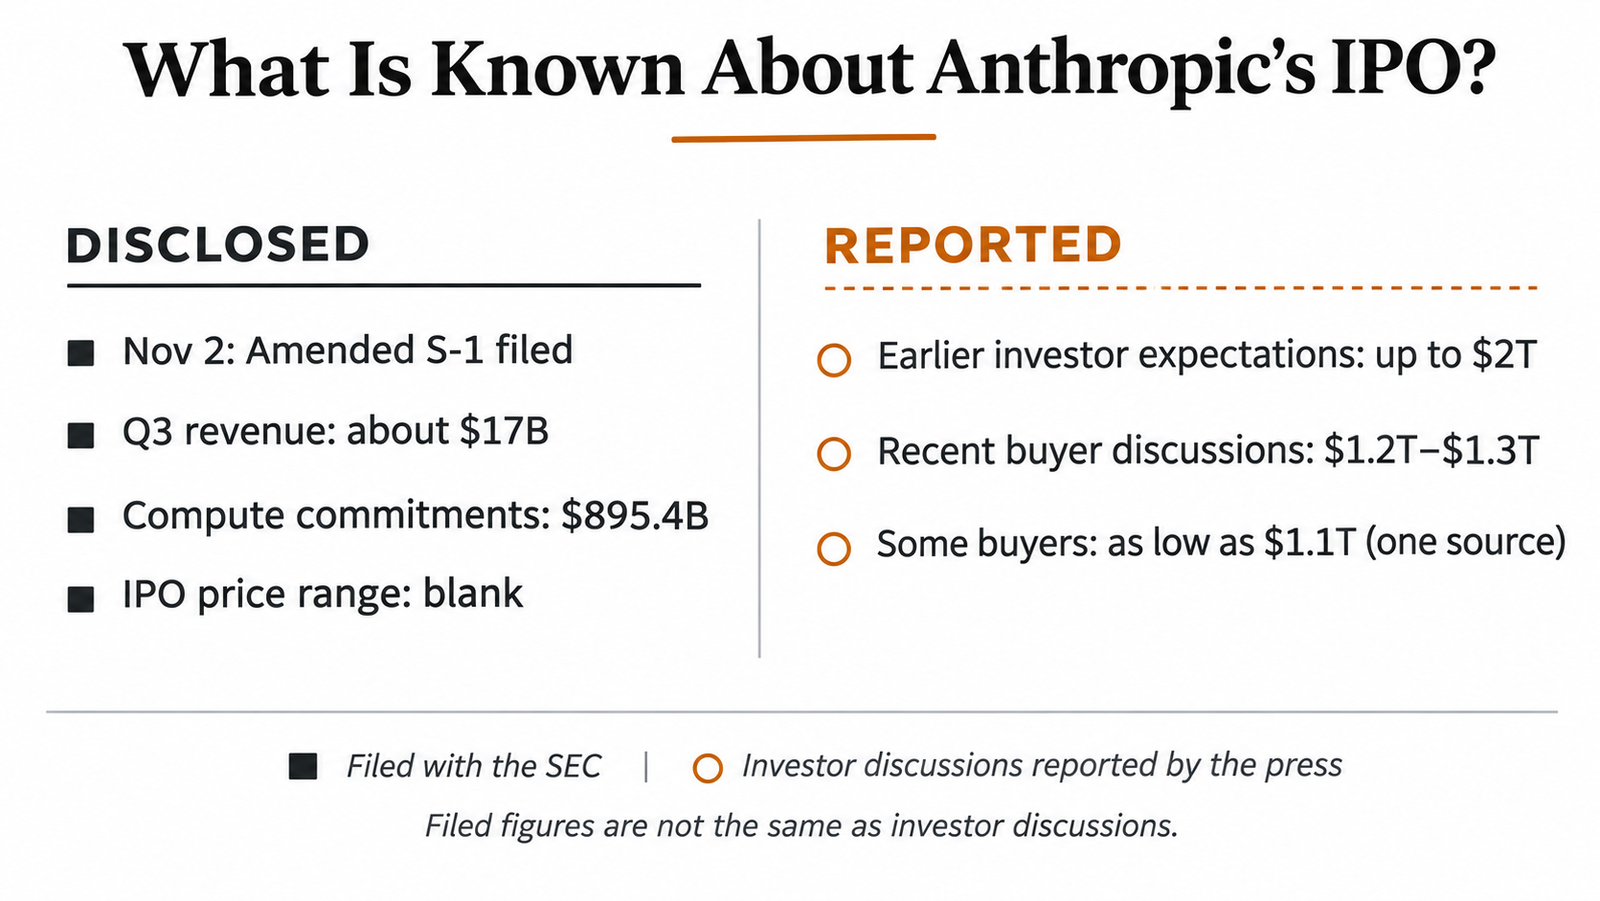
A month ago, some investors were reportedly talking about valuing Anthropic at up to $2 trillion. By 6 November, Bloomberg reported that prospective buyers were discussing a range of $1.2 trillion to $1.3 trillion, and that some were weighing $1.1 trillion. That is the headline version of the Anthropic IPO valuation story.

The filing tells a more useful one. Anthropic’s November 2 S-1/A shows $17.0 billion of revenue in a single quarter and a nine-month net loss of $104.0 billion, most of it non-cash. It also shows roughly $895.4 billion in aggregate compute and infrastructure commitments. Read together, those numbers explain more about the price buyers will pay than any single bid range does.

Key Takeaways
  • Valuation talk has fallen in reports, not filings: from up to $2 trillion earlier in the year to $1.2 trillion to $1.3 trillion, with one source citing $1.1 trillion.
  • The S-1/A confirmed fast growth and an operating loss: $16.96 billion of Q3 revenue, and a $567 million loss after a profitable Q2.
  • About 91% of the $104.0 billion nine-month net loss is a non-cash fair-value charge on convertible notes, which should end once the existing notes convert.
  • The $895.4 billion is a commitment schedule, not debt. Half of it is leases that have not commenced, and about $213.8 billion is conditional or terminable.
  • The 13.2x ratio shows scale, not solvency. The more useful test is $69.8 billion due in 12 months against $131.8 billion of cash and short-term investments.
  • Commitments could grow. The filing estimates a further $150 billion to $175 billion under arrangements with no fixed dollar figure.
  • Price, size and date are unconfirmed. All three are blank or absent in the filing.

Quick Navigation


Anthropic IPO valuation: what is confirmed and what is reported?

The figures in circulation come from very different places. Some are in a document Anthropic filed with the Securities and Exchange Commission. Others come from unnamed people describing investor conversations. This table keeps them apart.

ItemFigure or developmentEvidence status
Amended registration statementS-1/A (Amendment No. 1) filed 2 November 2026SEC-filed
Q3 2026 revenue$16.96 billion (three months to 30 September)SEC-filed
Nine-month 2026 revenue$33.24 billion, against $2.55 billion a year earlierSEC-filed
Aggregate commitmentsAbout $895.4 billion, substantially all compute and infrastructureSEC-filed
$1.2T to $1.3T valuation rangeDiscussed by prospective buyers, per Bloomberg, 6 NovemberAnonymous-source reporting
$1.1T lower endSome buyers weighing it, “one of the people said” (Bloomberg)Anonymous-source reporting
Earlier $2T expectationsInvestors expected up to $2 trillion earlier in the year, per ReutersPress-reported
Last private valuation$965 billion post-money, $65 billion Series H, 28 May 2026Company-disclosed
IPO timingRoadshow expected from the week of 9 November, pricing the week after, per ReutersAnonymous-source reporting
IPO price range and share countBlank in the amended filingSEC-filed (blank)
Commitments relative to revenueAbout 13.2 times annualised Q3 revenueCalculated
Disclosed figures come from the SEC filing; valuation ranges come from anonymous-source press reports and are not offering terms.

How the Anthropic IPO valuation talk changed

Three numbers mark the slide. Reuters reported that earlier in the year, investors expected an October listing at a valuation of up to $2 trillion. Bloomberg’s earlier reporting, as summarised by Investing.com, put the range investors had passed to bankers at $1.4 trillion to $1.5 trillion. Then, on 6 November, Bloomberg reported that potential buyers were discussing $1.2 trillion to $1.3 trillion, according to people familiar with the matter.

None of these is an official valuation, a filed figure, a trade or an IPO price. They describe what some buyers will discuss before formal marketing begins. For background on how the business looked before the filing, see our earlier analysis of Anthropic’s reported revenue and compute economics.

The Bloomberg report followed a sharp selloff on 5 November, when the Associated Press reported the Nasdaq composite down 4.5% in afternoon trading. AP linked the drop to rising borrowing costs, doubts about AI stock prices, and Democratic midterm gains that raised the prospect of curbs on data center construction.

What the November 2 S-1/A actually shows

The amended S-1 adds third-quarter results to the prospectus first made public on 26 October. Anthropic plans to list Class A shares on the Nasdaq Global Select Market under the symbol “ANT”. Goldman Sachs and Morgan Stanley head the underwriting list. The number of shares and the expected price range are still blank.

Revenue growth and the Anthropic IPO valuation

Revenue for the three months to 30 September was $16,956 million, against $1,382 million a year earlier. That is about 12.3 times the prior-year quarter, and 47% more than the $11,555 million reported for the June quarter. Nine-month revenue was $33.24 billion.

Operating results moved the other way in the latest quarter. Anthropic earned an operating profit of $974 million in Q2, then recorded an operating loss of $567 million in Q3. The filing attributes the swing mainly to $5.0 billion of compute bought under short-term commitments and a $2.0 billion non-cash charge tied to its employee donation matching programme.

Buying short-notice capacity suggests demand ran ahead of contracted supply. It also shows how fast compute costs can swing a quarter from profit to loss.

A $104 billion loss that is mostly not cash

The nine-month net loss of $104.0 billion looks alarming until you trace it. The filing says the accumulated deficit includes $94.3 billion of fair-value changes on convertible notes and derivative liabilities during the nine months, “driven by increases in our enterprise valuation”. In Q3 alone, that line was $21.9 billion of a $23.3 billion net loss.

These are accounting remeasurements. When Anthropic’s valuation rises, the notes are worth more to their holders and the company books a loss, but no cash leaves the business. The prospectus assumes the notes convert into shares immediately before the offering closes, which should end these charges on the existing notes. The filing also says Anthropic may issue up to $77.0 billion more in convertible notes, subject to conditions.

Other items need more care. Stock-based compensation was $3.3 billion over the nine months, and the donation charge was $2.0 billion. Neither is cash today, but both affect shareholders. The cash figures point the other way. Operating activities generated $6.6 billion in the first nine months of 2026, compared with $2.0 billion of cash used a year earlier.

The $895.4 billion figure behind the Anthropic IPO valuation

This is the number most easily misread. The filing describes “an aggregate committed spend of approximately $895.4 billion, substantially all of which is related to compute and infrastructure”. About $447.5 billion is expected before 31 December 2030, and “substantially all of the remainder” between 2031 and 2045.

It is not debt, money already spent, or a single year’s expense, and most of it is not on the balance sheet. It is a schedule of future purchases and leases, often agreed before the capacity is built.
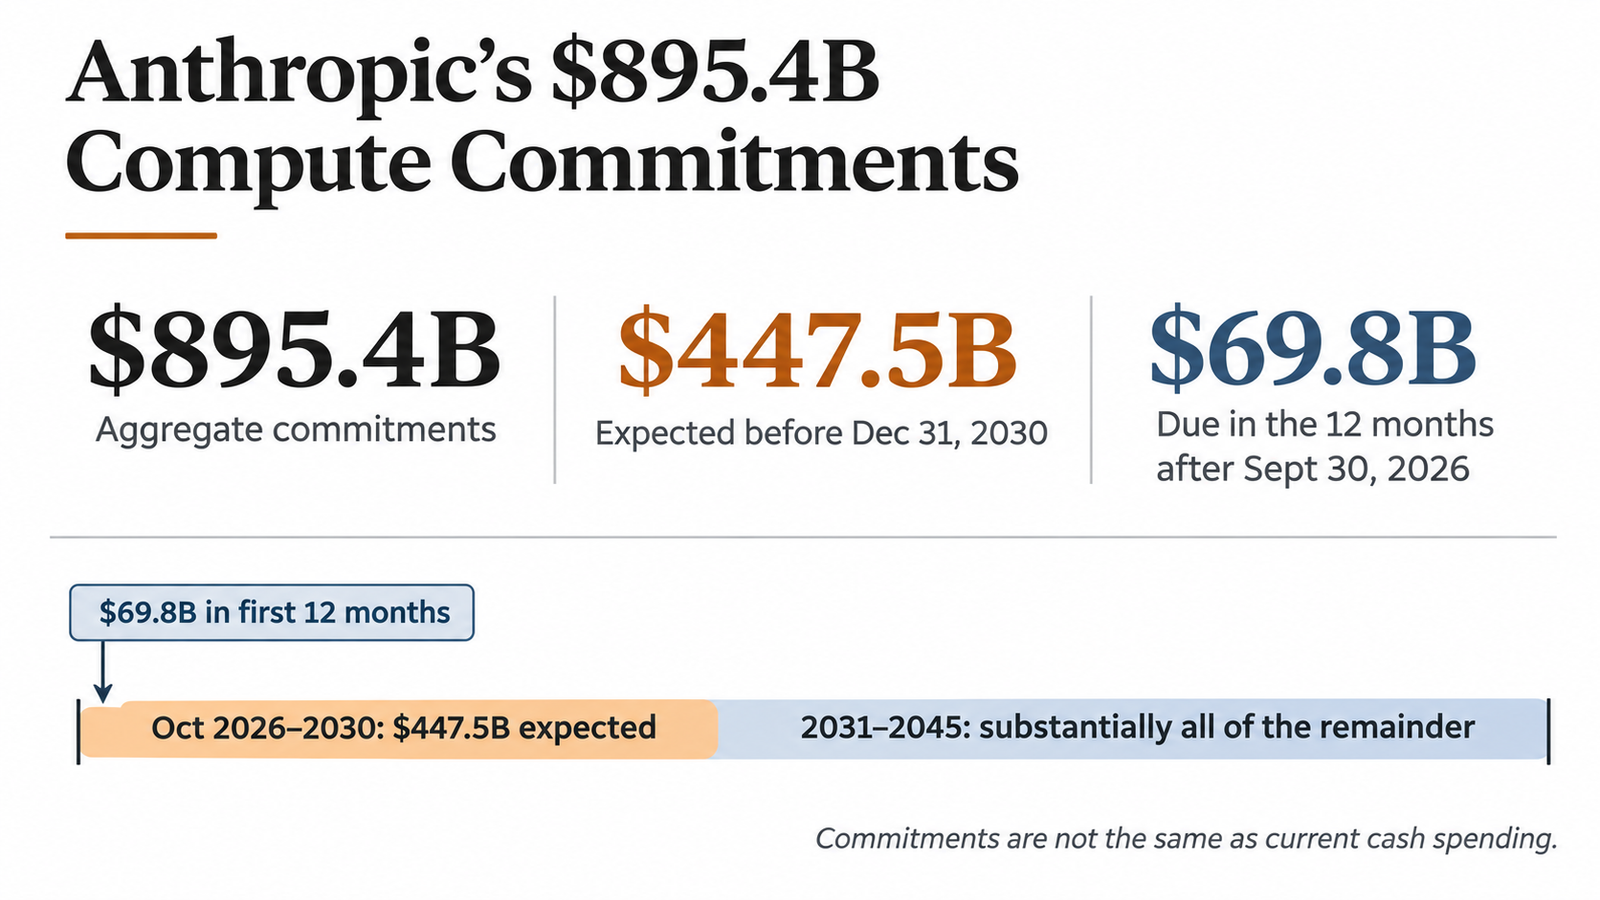
The three figures are nested: the $69.8 billion falls within the $447.5 billion, which falls within the $895.4 billion. Source: Anthropic S-1/A, 2 November 2026.
How the $895.4 billion adds up

The contractual obligations section of the filing lets us rebuild the total. Our addition of the parts comes to $895.39 billion:

ComponentAmountWhat it is
Fixed obligations at 30 September$320.0 billionPurchase commitments of $313.8 billion plus operating and finance leases of $6.2 billion
Leases signed but not yet commenced$451.2 billionMostly expected to begin between 2026 and 2028, with terms up to 20 years
Commitments signed after 30 September$100.2 billionMainly data center leases and cloud hosting agreements
Short-term contracts$24.0 billion$17.4 billion at quarter end plus $6.6 billion signed afterwards

Half the headline, about 50.4%, is leases that have not started. Only about 36% sits in the payment table as of the balance-sheet date. The rest was added later or will only become an obligation when a facility is delivered. This is a large jump from the $518 billion figure reported from the confidential draft in October, which we covered in Anthropic’s earlier $518 billion infrastructure commitments.

The named contracts show the scale: at least $110.0 billion with Amazon through April 2036, about $121.3 billion with Google through July 2033 and at least $44.9 billion with Microsoft through June 2033. Each applies “regardless of actual usage”.

The filing also lists arrangements that are not in the $895.4 billion because they carry no fixed dollar commitment. It estimates payments under these at about $150 billion to $175 billion. It gives separate estimates for extra Google TPU capacity ($125 billion to $150 billion) and an AMD agreement (more than $20 billion), both outside the $895.4 billion. The headline may understate eventual spending even as parts of it stay conditional.

Not all of the total is locked. The filing says about $213.8 billion, roughly 24%, is subject to exercisable termination rights or to conditions before the arrangement begins, such as a counterparty securing financing, sites or regulatory approval. In general, Anthropic can also terminate if counterparties miss delivery dates.

That flexibility cuts both ways. Terms that let Anthropic walk away if a data center is late also mean some planned capacity may never arrive.

Anthropic Direct and the case for locking in capacity

The filing describes a shift from cloud contracts toward what Anthropic calls Anthropic Direct: leasing chips directly and hosting them in dedicated facilities run on its behalf. It says this allows the company “to separate our commitments for data center capacity from our commitments for the compute infrastructure deployed inside them”.

Data centers take years to build but are the smaller part of compute cost, so securing buildings early and buying chips later keeps the costliest decisions open. The trade-off is rigidity: leases of up to 20 years are hard to unwind if demand slows.

The filing also says some data center projects rely on “financing sources or partners who guarantee the lease obligations”. Fortune’s 4 November analysis argues that this shifts part of the risk onto chip suppliers. It is part of the financing pressures across AI infrastructure that have pushed some bond investors to demand higher yields.

The 13.2x comparison: useful for scale, easy to misuse

Here is the calculation behind a figure that has circulated widely:

  • Q3 revenue: $16.956 billion × 4 = $67.8 billion annualised
  • $895.4 billion ÷ $67.8 billion = about 13.2 times

That ratio is a scale illustration. The $67.8 billion annualises one quarter; it is not a forecast or reported annual revenue. The $895.4 billion spans almost two decades. The result is not a debt-to-revenue ratio, an enterprise-value multiple or a solvency test.

Better comparisons look at matching time frames. The filing says about $69.8 billion of obligations is expected to be paid in the 12 months after 30 September. That is roughly equal to one year of revenue at the Q3 rate (about 103%). It is also about 1.8 times the annualised Q3 compute and infrastructure expense of $39.5 billion. These are our calculations, and both comparisons assume revenue stays flat, which recent quarters suggest it won’t.

The pre-2030 figure gives a second view. A simple average of $447.5 billion over the roughly four and a quarter years to the end of 2030 is about $105 billion a year. That is an illustration, not a schedule. The filing’s own table shows payments rising from $29.2 billion in 2027 to $47.8 billion in 2029, before the leases not yet commenced are added.

Why buyers may want a lower Anthropic IPO valuation

The evidence points to several pressures at once, without showing which matters most. The market backdrop is the clearest. Bloomberg tied the lower bids directly to the post-election selloff. Reuters, citing four people familiar with investor discussions, reported that some potential buyers see $1.5 trillion as the top of their range and want a bigger discount. Truist’s Keith Lerner, quoted by Reuters, called the mood “a buyers’ strike in tech”.

Company-specific concerns also feature. Reuters reported investor attention on Anthropic’s record of quarterly losses, its capital needs and its large commitments to partners. Investors also want an October revenue figure to judge whether growth has picked up again after a recent slowdown.

At $1.2 trillion, Anthropic would be valued at about 17.7 times annualised Q3 revenue. At $2 trillion, the figure would be about 29.5 times. These are our calculations, and they ignore whether the reported figures are pre- or post-money.

The private round adds another reference point. Anthropic raised $65 billion at a $965 billion post-money valuation in May, per Reuters. Even the $1.1 trillion lower end is about 14% higher. The two figures are not directly comparable, though. A private round prices preferred shares with negotiated rights, while an IPO prices common stock in an open market and adds new shares.

Cash, liquidity and the Anthropic IPO valuation

Profitability and liquidity are different questions. Anthropic is not consistently profitable on an operating basis, but it holds a lot of cash.

At 30 September, the filing shows $95.6 billion of cash and cash equivalents and $36.3 billion of short-term investments. It also shows $14.8 billion available under a $15.0 billion revolving credit facility that matures in 2031. Cash and short-term investments of $131.8 billion cover the $69.8 billion due over the next 12 months about 1.9 times.

That cushion came mostly from investors, not from operations. Financing activities brought in $110.7 billion over the nine months. Investing activities used $36.5 billion, mainly to buy short-term securities. Spending on property and equipment was only $925 million, plus $2.0 billion of prepayments for leased assets.

The filing warns this will change. It expects more compute investment to need “significant upfront payments” before the compute is operational, and significant net cash outflows “for the foreseeable future”. It says its resources cover at least the next 12 months.

What the IPO could change

The filing says the offering aims to increase Anthropic’s “capitalization and financial flexibility” and create a public market for its shares. Proceeds are for general corporate purposes, including “investments in compute and infrastructure”. Reuters reported that some expect the deal to raise as much as $100 billion, although the filing gives no amount.

A listing would convert the existing notes and end their fair-value charges, making net income easier to read. It would give Anthropic a public currency for future raises. It would also reprice the company daily, so the commitment schedule is judged every quarter rather than once per funding round.

What the Anthropic IPO valuation debate can’t answer yet

Several facts that would settle the argument are not public. The price range and share count are blank. The split between new shares and shares sold by existing holders is unknown, which determines how much cash Anthropic actually raises.

The filing does not give a year-by-year schedule for the $451.2 billion in leases not yet commenced. Nor does it say how the $150 billion to $175 billion of variable arrangements will be phased. Most importantly, nobody outside the company knows how much of the contracted capacity will be needed by the time it arrives.

What to Watch Next

These would change this analysis, roughly in the order they are likely to appear:

  1. The next S-1 amendment: any change to the $895.4 billion or the $69.8 billion due in 12 months.
  2. The price range: the first company-set valuation signal, replacing press-reported ranges.
  3. The share count: needed to turn a price into a market capitalisation.
  4. New versus selling-stockholder shares: how much cash reaches Anthropic.
  5. The pricing date: a slip past the reported November window would be material.
  6. Updated financials, including the October revenue investors reportedly want.
  7. Timing changes confirmed by the company or a filing, not by sources.
  8. Revised investor discussions, treated as reporting, not offering terms.

FAQ

What is the Anthropic IPO valuation in 2026?

There isn’t one yet; the S-1/A leaves the price range blank. Bloomberg reported on 6 November, citing unnamed sources, that buyers were discussing $1.2 trillion to $1.3 trillion.

Why has the reported Anthropic IPO valuation fallen?

Reports link it to the AI stock selloff after the US midterms and to concerns about losses and compute commitments. Which factor weighs most is unclear.

Is the Anthropic IPO valuation higher than its last private valuation?

Based on reported discussions, yes. Anthropic’s May 2026 round valued it at $965 billion post-money. Even $1.1 trillion would be about 14% higher, though private and public valuations are not directly comparable.

How much revenue did Anthropic report in Q3 2026?

$16.96 billion for the three months to 30 September 2026, according to the S-1/A. That is about 12 times the $1.38 billion reported a year earlier.

What are Anthropic’s $895.4 billion compute commitments?

Purchase commitments and leases, substantially all for compute and infrastructure, including leases not yet started. About $447.5 billion falls before 2031 and most of the rest between 2031 and 2045.

Is the $895.4 billion current debt?

No. Most of it is future spending under contracts and leases that have not begun. About $69.8 billion is expected to be paid in the 12 months after 30 September 2026.

Has the Anthropic IPO valuation or price been set?

No. The price range is blank, and reported figures are investor discussions, not offering terms.

When is Anthropic expected to go public?

Reuters reported a roadshow from the week of 9 November and pricing the week after, while noting investor doubts about that timing. Anthropic has not confirmed a date.

Why do compute commitments matter to the Anthropic IPO valuation?

They lock in large future costs before the revenue to pay for them exists. Buyers have to judge whether demand will grow fast enough to use the capacity Anthropic has contracted.

What would change this Anthropic IPO valuation analysis?

A filed price range, the share count, the split between new and existing shares, and any change to the commitment figures in the next S-1 amendment.

This article is for informational and educational purposes only. It is not investment advice, a recommendation to buy or sell securities, or a prediction of Anthropic’s IPO valuation or share price. Reported investor discussions should not be interpreted as confirmed offering terms.


Keep reading

AGI vs superintelligence

AGI vs Superintelligence: A New Name Isn’t a New Intelligence
Facts checked against official documents and reporting on 18 November 2026. On 29 September, the White House told federal agencies to stop writing “artificial intelligence” …
AI Coding Agent

AI Coding Agents Are Getting Expensive. Who’s Paying for the Tokens?
Pricing checked on official vendor pages on 17 November 2026. All USD. Cost scenarios are illustrative and labelled as such. On 28 October, TechCrunch published …
Model Weights

Verify Model Weights: 7 Checks Before You Download
Checked against the burner22/numbat repository and its discussions, Hugging Face and PyTorch documentation, and Moonshot AI’s announcement on 2 November 2026. On 1 November, a …
Agentic AI Statistics

30 Agentic AI Statistics for 2026: Adoption, Spending and Risk

Last updated: 15 November 2026. This page is updated monthly; each figure keeps its original publication date. Agent traffic at one healthcare booking platform rose …

Anthropic IPO: Revenue, Compute Costs and the November Timeline

Anthropic IPO

Anthropic told prospective investors on 14 October that it earned $16.8 billion in revenue in the third quarter of 2026. It also said it earned $1.70 for every dollar it spent on computing power in that quarter. Those two numbers, reported by Reuters, Bloomberg and the Financial Times from people who attended the meeting, are the strongest case yet for an Anthropic IPO. They’re also harder to read than they look.

The difficulty is the third number. A confidential prospectus seen by Reuters in September showed that Anthropic has committed at least $518 billion to computing infrastructure over roughly a decade, and that about 80% of it can’t be cancelled. So the question for anyone weighing the listing isn’t whether revenue is growing. It’s whether revenue per compute dollar can keep rising faster than the bills Anthropic has already signed.

Status as of 18 October 2026: Anthropic has officially confirmed only that it confidentially submitted a draft S-1 on 1 June 2026. It has announced no IPO date, share count or price. A November listing has been reported by the Wall Street Journal and Bloomberg, citing unnamed sources, but it isn’t confirmed. We found no report of a public S-1 on the SEC’s EDGAR database. All financial figures below come from investor-day attendees or a confidential prospectus, not from audited public filings.

Key Takeaways
  • Confirmed: Anthropic submitted a confidential draft S-1 on 1 June 2026. It has not announced an IPO date.
  • Reported: Quarterly revenue rose from about $4.7 billion in Q1 2026 to $16.8 billion in Q3. Growth slowed from roughly 147% in Q2 to about 45% in Q3.
  • Reported: Anthropic said it was profitable on an adjusted basis and cash-flow positive in Q3, but the adjustments haven’t been fully disclosed.
  • Our analysis: A $1.70 revenue-to-compute ratio implies compute equal to about 59% of revenue. That can’t sit alongside an 85% gross margin unless most compute, probably training, is booked outside cost of revenue.
  • Reported: About 80% of the $518 billion in commitments is non-cancelable or payable regardless of use. Payment schedules haven’t been reported.
  • Unresolved: A mid-November listing would need a public S-1 by late October. Whether that happens is the next hard signal.

Quick Navigation


The numbers behind the Anthropic IPO story

The quarterly figures come from an investor day at Anthropic’s San Francisco headquarters on 14 October. Reuters cited two attendees, and Bloomberg cited people familiar with the presentation. Anthropic didn’t respond to Reuters’ request for comment and hasn’t published the results. The figures are calendar 2026 quarters. They describe revenue earned in each quarter, not an annualised run rate.

Quarter (2026)Reported revenueChange on prior quarter (our calculation)Source and qualification
Q1$4.7bn (FT: about $4.8bn)n/aInvestor-day attendees
Q2$11.6bn (FT: $11.5bn)+147% (FT figures: +140%)Investor-day attendees
Q3$16.8bn+45% (FT figures: +46%)Reuters, Bloomberg and FT all report $16.8bn

The small differences between outlets matter less than what they agree on. Revenue for the first nine months of 2026 comes to $33.1 billion on either set of figures. That’s about 7.2 times the roughly $4.6 billion Anthropic earned in all of 2025, according to the prospectus Reuters reviewed.

The slowdown is just as clear. Q2 more than doubled Q1, while Q3 added 45%. The Decoder linked the slower quarter to a summer seasonal dip and new competition. Anthropic also told investors that 5% to 7% of revenue came from distillation, meaning rival labs paying to train on Claude’s outputs. Per the FT, as summarised by Simon Willison, it had cut that business back “materially” in Q3. That’s revenue the company is choosing to shrink.

One accounting point affects every ratio that follows. Anthropic records the full value of Claude sales made through cloud partners such as AWS and Google, and books the partners’ share as an expense. OpenAI records only its net share. Axios reported that a source familiar with Anthropic’s finances put the effect of switching to net reporting at about 6% to 10% of revenue. The S-1 should settle the treatment. Until then, comparisons with OpenAI need that caveat.

What the reported compute ratio actually tells us

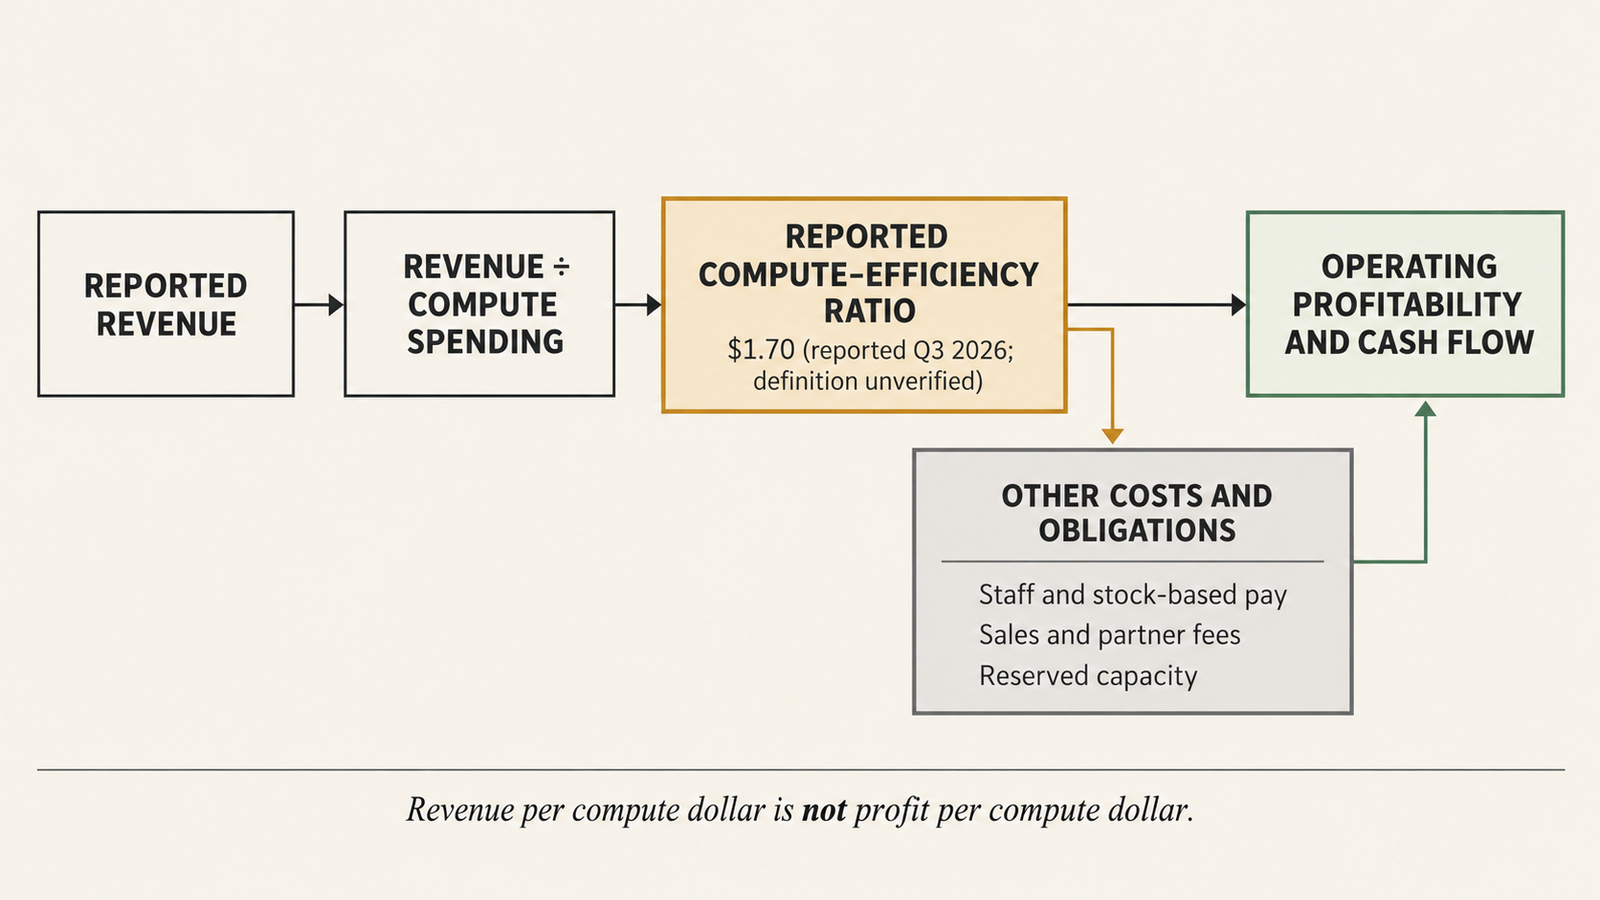
According to the FT’s investor-day reporting, Anthropic earned $1.70 in revenue for every dollar spent on “computing power” in Q3. It’s the most useful number in the story, and the most easily misread.

Start with what it can’t mean. A ratio of 1.70 doesn’t mean Anthropic keeps 70 cents of profit per compute dollar. Revenue also has to pay for staff, sales, cloud-partner fees, offices, legal costs and stock-based compensation. The ratio measures how hard the hardware is working commercially, not how profitable the company is.

If the ratio uses Q3 revenue and Q3 compute spending, the arithmetic is straightforward. These are our calculations, and they depend on that assumption:

Implied Q3 compute spend = $16.8bn ÷ 1.70 ≈ $9.9bn
Compute as a share of revenue = 1 ÷ 1.70 ≈ 59%
2025 equivalent = $4.6bn revenue ÷ $7.33bn compute and infrastructure costs ≈ $0.63

The 2025 figures come from the confidential prospectus as reported by Reuters. On that basis, Anthropic went from earning 63 cents per compute dollar in 2025 to $1.70 in Q3 2026, close to a 2.7-fold improvement. If the definitions match, that’s the clearest evidence in the reporting that the business is scaling. Revenue grew much faster than the hardware bill.

The tension with an 85% gross margin

Now set it beside the 85% gross margin Bloomberg reported. Gross margin is revenue minus cost of revenue, divided by revenue. At 85%, cost of revenue in Q3 would be at most about $2.5 billion. But the ratio implies about $9.9 billion of compute. If all of that compute counted as cost of revenue, the gross margin couldn’t exceed about 41%.

Both numbers can be true only if roughly three-quarters of the compute spend, around $7.4 billion, sits outside cost of revenue. The likeliest home is training, which AI companies often treat as research and development. Earlier reporting cited by BeInCrypto described an 80% gross margin that “left out training costs,” which fits that reading. It hasn’t been confirmed for the 85% figure.

That doesn’t make the gross margin misleading. It means it measures something narrow: the cost of serving models already built. The $1.70 ratio is the broader test, because it appears to count all computing power. To interpret it fully, readers need four things the S-1 should disclose:

  • whether “computing power” includes training, inference and research compute together;
  • whether it includes payments on reserved but idle capacity;
  • whether revenue is gross of cloud-partner fees, which would flatter the ratio (on a 6% to 10% net-basis haircut, $1.70 becomes about $1.53 to $1.60);
  • whether the Q3 figure is typical or flattered by timing, such as a training run that hadn’t started.
Anthropic IPO

The $518 billion question: commitments are not spending

The $518 billion figure comes from the confidential prospectus Reuters reviewed on 29 September. It isn’t debt, and it isn’t money already spent. It’s the total of contracts to buy computing capacity and equipment over roughly a decade. That’s why it doesn’t contradict a cash-positive quarter: the obligations fall due over years, while the quarter’s cash flow covers one quarter’s payments.

CounterpartyReported commitmentPeriodCancelability, as reported
Broadcom (equipment leases)~$161.2bnIncludes a five-year, $125.2bn TPU leaseNon-cancelable except on default
Google$111.1bnApr 2026 to Jul 2033Payable regardless of usage
Amazon$110bnMay 2026 to Apr 2036Payable regardless of usage
xAI (Nvidia-based capacity)Up to $84.5bnThrough 2029Largely cancelable with 90 days’ notice
Microsoft$31.4bnNov 2026 to May 2033Non-cancelable except for Microsoft’s uncured breach
AMDExpected to exceed $20bnNot reportedAMD also agreed to buy up to $5bn of Anthropic stock

The first four non-cancelable lines add up to about $414 billion. That matches the prospectus’s statement that about 80% of the total “is non-cancelable or requires payment regardless of usage.” Anthropic’s own wording on Google is blunt: “If our actual spend falls short, we must pay Google the difference.”

That is take-or-pay exposure. If demand falls short of the commitment, Anthropic pays anyway, and the unused capacity drags the revenue-per-compute ratio down. Our earlier analysis of the obligation behind Anthropic’s $518 billion compute commitment goes through each partner’s terms in detail.

Anthropic IPO
What the commitments assume about revenue

A rough scale check helps, as long as it’s treated as an illustration, not a schedule. Spreading each non-cancelable contract evenly over its reported period gives about $56 billion a year. That counts Google over about seven years, Amazon over ten, Microsoft over six and a half, and only the five-year Broadcom TPU lease. Anthropic’s annualised Q3 compute spend, at four times the implied $9.9 billion, is about $40 billion. To keep the ratio at $1.70 against $56 billion a year of compute, annual revenue would need to reach about $95 billion. Q3 annualised is $67 billion.

The real schedules almost certainly aren’t flat. Capacity typically ramps as data centres come online, so early years are lighter. But the illustration shows what the commitments assume: revenue keeps growing well beyond its current pace. A slowdown from 147% to 45% in a quarter is the kind of shift that makes that assumption worth testing.

Where CoreWeave fits into the picture

CoreWeave announced a multi-year agreement with Anthropic on 10 April 2026 to run production Claude workloads. It disclosed no contract value, duration or capacity. CoreWeave isn’t named in the reported six-partner breakdown of the $518 billion, so we can’t tell whether that contract sits inside the total, is too small to list, or is reported elsewhere.

The October “repricing” is a different event. It concerns CoreWeave’s own debt. Its bonds fell far enough that yields reached roughly 15% to 16% on 14 and 15 October, while the fixed coupons stayed the same, as we detailed in our analysis of CoreWeave’s debt repricing. Nothing we found shows any change to CoreWeave’s agreement with Anthropic.

The connection is indirect but real. Lenders are charging more to finance GPU-heavy infrastructure. Anthropic’s largest commitment, the Broadcom TPU lease, is itself funded by a roughly $60 billion debt structure that Bloomberg reported. If the cost of financing AI capacity rises, providers will try to pass it on when contracts renew or expand. That’s a pressure on future compute prices, not evidence about Anthropic’s current terms.

What profitability and free cash flow do, and don’t, prove

Anthropic told investors it was profitable “on an adjusted basis” in Q3. The FT reported it was the second straight such quarter. Bloomberg reported an adjusted operating margin of “over 11%” and positive free cash flow. Free cash flow is operating cash flow minus capital spending.

Each of those claims is narrower than it sounds.

  • Adjusted isn’t GAAP. The FT and The Information both reported that the adjusted margin excludes stock-based compensation, which is a real cost even though no cash leaves the company: it dilutes shareholders. Other adjustments haven’t been disclosed. The 2025 comparison shows how far the measures can diverge. On the prospectus figures Reuters reported, Anthropic’s 2025 operating loss was more than $8 billion before liability writedowns. Its net loss was about $42 billion, of which about $34 billion was a non-cash charge on convertible financing.
  • The margin’s period is unclear. Bloomberg’s “over 11%” reads as a Q3 figure. The Decoder, citing The Information, described 11% as the margin for the year through Q3. Those are different claims, and the reporting doesn’t settle which is right.
  • Cash flow can be front-loaded. Large customers sometimes prepay, and capacity contracts can defer payments until hardware arrives. Either would make a quarter’s cash flow look stronger than the underlying economics. No cash-flow amount has been reported, so there’s no way to tell. Anthropic ended 2025 with $20.28 billion in cash, according to the prospectus as reported, and it isn’t short of money. The IPO is about funding commitments that grow faster than current cash generation.
What the reported margins add up to

The useful reading is this. If 11% adjusted operating margin and $1.70 per compute dollar both describe Q3, compute took about 59% of revenue. Everything else before stock-based pay took about 30%, leaving roughly $1.8 billion of adjusted operating profit. That’s a real business at real scale. It’s also thin enough that a few points of compute cost or a quarter of idle capacity would erase it.

The Anthropic IPO timeline: confirmed facts and reported expectations

Date (2026)EventStatus
1 JuneAnthropic confidentially submits a draft S-1; shares and price not setOfficial
18 SeptemberWSJ reports a November IPO plan, per PYMNTSAnonymous sources
29 SeptemberReuters reports the confidential prospectus: $518bn of commitments, 2025 resultsDocument seen by Reuters, not public
1 OctoberBloomberg: listing as soon as mid-November; marketing could start the week of 9 November, per Yahoo FinanceAnonymous sources; plans “remain fluid”
4 OctoberNo public S-1 on EDGAR, 126 days after the confidential submissionSecondary check
14 OctoberInvestor day in San Francisco; Q3 figures sharedReported by attendees
15 OctoberReuters: some investors weigh a valuation near $1.5 trillion, below the roughly $2 trillion earlier expectedAnonymous sources

The November timeline is unconfirmed. Anthropic hasn’t announced it, and Bloomberg itself said the dates could change.

There is a mechanical test, though. A company that files confidentially must make its registration statement public at least 15 days before it starts a roadshow, as Yahoo Finance noted. Marketing in the week of 9 November would therefore need a public S-1 by about 25 October. We couldn’t query EDGAR directly for this article, and we found no report of a public filing as of 18 October. That isn’t proof that nothing has been filed confidentially since. Amended drafts can be submitted privately too.

What to watch before the Anthropic IPO

  • A public S-1 on EDGAR. It would turn reported figures into audited ones, and its timing confirms or kills the November window.
  • The definition of compute cost. The S-1’s segment and cost disclosures should show whether training sits in cost of revenue or R&D. That decides whether 85% gross margin and $1.70 per compute dollar describe the same business.
  • The commitment schedule. The contractual obligations table would show how much of the $518 billion falls due each year. Back-loaded payments buy time; front-loaded payments test revenue growth sooner.
  • Q4 growth and distillation. Anthropic reportedly told investors that lower distillation revenue will weigh on the current quarter. A further slowdown would sharpen the commitments question.
  • Gross versus net revenue. If the SEC pushes for net reporting of cloud-partner sales, every ratio here moves down by a similar amount.
  • Stock-based compensation. Its size determines the gap between adjusted and GAAP operating profit.

Conclusion

The reported numbers support one conclusion. Anthropic has turned compute into revenue far more efficiently in 2026 than in 2025, and on an adjusted basis that is now enough to cover its other costs.

They don’t yet show that the efficiency will hold against $414 billion of commitments that must be paid whether or not the demand arrives. That depends on two disclosures only a public S-1 can provide: what “computing power” includes, and when the commitment payments fall due. Until those appear, the $1.70 ratio is the right number to watch and the wrong number to treat as settled.

Frequently Asked Questions

Is Anthropic going public?

It is preparing to. Anthropic confidentially submitted a draft S-1 on 1 June 2026, which gives it the option to list after SEC review. It hasn’t announced an IPO date or terms.

When is Anthropic expected to IPO?

Bloomberg and the Wall Street Journal reported a November 2026 target, with trading possibly before Thanksgiving. Both cited unnamed sources, and Anthropic hasn’t confirmed the timing.

Has Anthropic filed an S-1?

Only confidentially, on 1 June 2026. Reuters has reported on a prospectus it saw, but no public S-1 had appeared on EDGAR in the reporting we found as of 18 October 2026. Our explainer on what the Anthropic S-1 must disclose covers how that filing process works.

How much revenue does Anthropic generate?

Investor-day attendees reported $16.8 billion for Q3 2026 and about $33.1 billion for the first nine months. These figures aren’t audited or published by Anthropic.

Is Anthropic profitable?

On an adjusted basis, reportedly yes, for Q2 and Q3 2026. The adjustments exclude stock-based compensation at least. In 2025, it reported a large operating loss and a net loss of about $42 billion, according to the prospectus Reuters saw.

How much is Anthropic spending on compute?

Reported 2025 compute and infrastructure costs were $7.33 billion. No Q3 figure has been reported, but the $1.70 ratio implies about $9.9 billion if it uses same-quarter figures. That’s our calculation, not a disclosed number.

What does the $1.70 revenue-per-compute-dollar figure mean?

It reportedly means Q3 revenue was 1.7 times compute spending. It measures revenue efficiency, not profit, because staff, sales and other costs also come out of revenue.

What are Anthropic’s infrastructure commitments?

At least $518 billion over about a decade with six partners, per the confidential prospectus Reuters saw. About 80% is non-cancelable or payable regardless of usage. These are future obligations, not current spending or debt.


Keep reading

AGI vs superintelligence

AGI vs Superintelligence: A New Name Isn’t a New Intelligence

Facts checked against official documents and reporting on 18 November 2026. On 29 September, the White House told federal agencies to stop writing “artificial intelligence” …
AI Coding Agent

AI Coding Agents Are Getting Expensive. Who’s Paying for the Tokens?

Pricing checked on official vendor pages on 17 November 2026. All USD. Cost scenarios are illustrative and labelled as such. On 28 October, TechCrunch published …
Model Weights

Verify Model Weights: 7 Checks Before You Download
Checked against the burner22/numbat repository and its discussions, Hugging Face and PyTorch documentation, and Moonshot AI’s announcement on 2 November 2026. On 1 November, a …
Agentic AI Statistics

30 Agentic AI Statistics for 2026: Adoption, Spending and Risk

Last updated: 15 November 2026. This page is updated monthly; each figure keeps its original publication date. Agent traffic at one healthcare booking platform rose …

Announced vs Delivered Megawatts: Data Centre Capacity Delivery

data centre capacity delivery

Bloomberg reported on 15 October that Nscale’s flagship data centre at Glomfjord, just north of the Arctic Circle in Norway, was running about six months behind schedule. Only 6.4 MW of a planned 30 MW were in operation, according to accounts of the report. The timing matters. A month earlier, the British neocloud had filed to list on the New York Stock Exchange, reportedly targeting a valuation of up to $35 billion. Its filing showed $103.4 billion of contracted value, of which only $2.6 billion was active. Data centre capacity delivery, the slow conversion of announced megawatts into compute that customers use and pay for, is the variable underneath that gap. The industry routinely reports it as if it were a single number.

Key Takeaways
  • The reported numbers give 21.3%, not a completion rate. 6.4 MW running against 30 MW planned is 21.3% of the plan, or a 23.6 MW difference. Neither figure’s definition has been published, so that’s arithmetic, not a progress score.
  • The site’s customer is ByteDance, not Microsoft. Reports citing Bloomberg say Glomfjord is being built for ByteDance. Microsoft’s contracted Norway capacity is at a separate Narvik site due in 2027.
  • Nscale’s own figures disagree. The company’s website lists Glomfjord as “30 MW operational.” Bloomberg reports 6.4 MW running. Both can be true only if they measure different things.
  • Contract value runs well ahead of active revenue. Nscale’s filing shows $2.6 billion active out of $103.4 billion contracted, and about 25,000 active GPUs out of 461,000 active or contracted.
  • Delay costs money before it costs revenue. Bloomberg reports penalties of millions of dollars, settled with better terms on new contracts. The filing lets Anthropic cancel tranches delivered too late.
  • Capacity should be reported by milestone. Announced, energised, commissioned, accepted and serving workloads are different facts, and investors need each one stated separately.

Quick Navigation


Two numbers that don’t measure the same thing

Start with the arithmetic, because it is the only part that can be stated with certainty. 6.4 divided by 30 is 21.3%. The difference is 23.6 MW. What those numbers mean is harder to say.

Bloomberg’s report, as relayed by Quartz and DCD, describes 30 MW as planned and 6.4 MW as running. It doesn’t say whether either figure is IT load (power available to servers), total facility power including cooling, or grid connection capacity. These can differ substantially. A site with a 30 MW grid connection may support noticeably less IT load once cooling and electrical losses are counted.

The company’s own description adds to the confusion. Nscale’s Glomfjord page lists the site as “30 MW operational” and “expandable to 60 MW.” In March 2025, DCD reported that Nscale and InfraPartners would add a 30 MW liquid-cooled building next to the existing 30 MW, set to “go live in Q2 2025.” One plausible reading is that Bloomberg’s planned 30 MW refers to that new building rather than the whole campus. If so, an older facility is operating alongside it. That would make the 21.3% a measure of the expansion only. We couldn’t confirm it, and Nscale declined to comment to Bloomberg, citing its pre-IPO quiet period.

The customer is also different from what’s often assumed. Microsoft is Nscale’s biggest contracted customer overall: its agreements provide for payments of up to about $43.8 billion through December 2033, according to the filing as reported by TokenPost. But reports citing Bloomberg say Glomfjord is being built for ByteDance. Tom’s Hardware found that a ByteDance subsidiary, Spring (SG), accounted for 73% of Nscale’s 2025 revenue through 2,304 Nvidia B200 GPUs at the site. Microsoft’s Norway capacity is at Narvik, a 230 MW joint-venture site with Aker that is due to deliver in 2027.

A seven-step audit of data centre capacity delivery

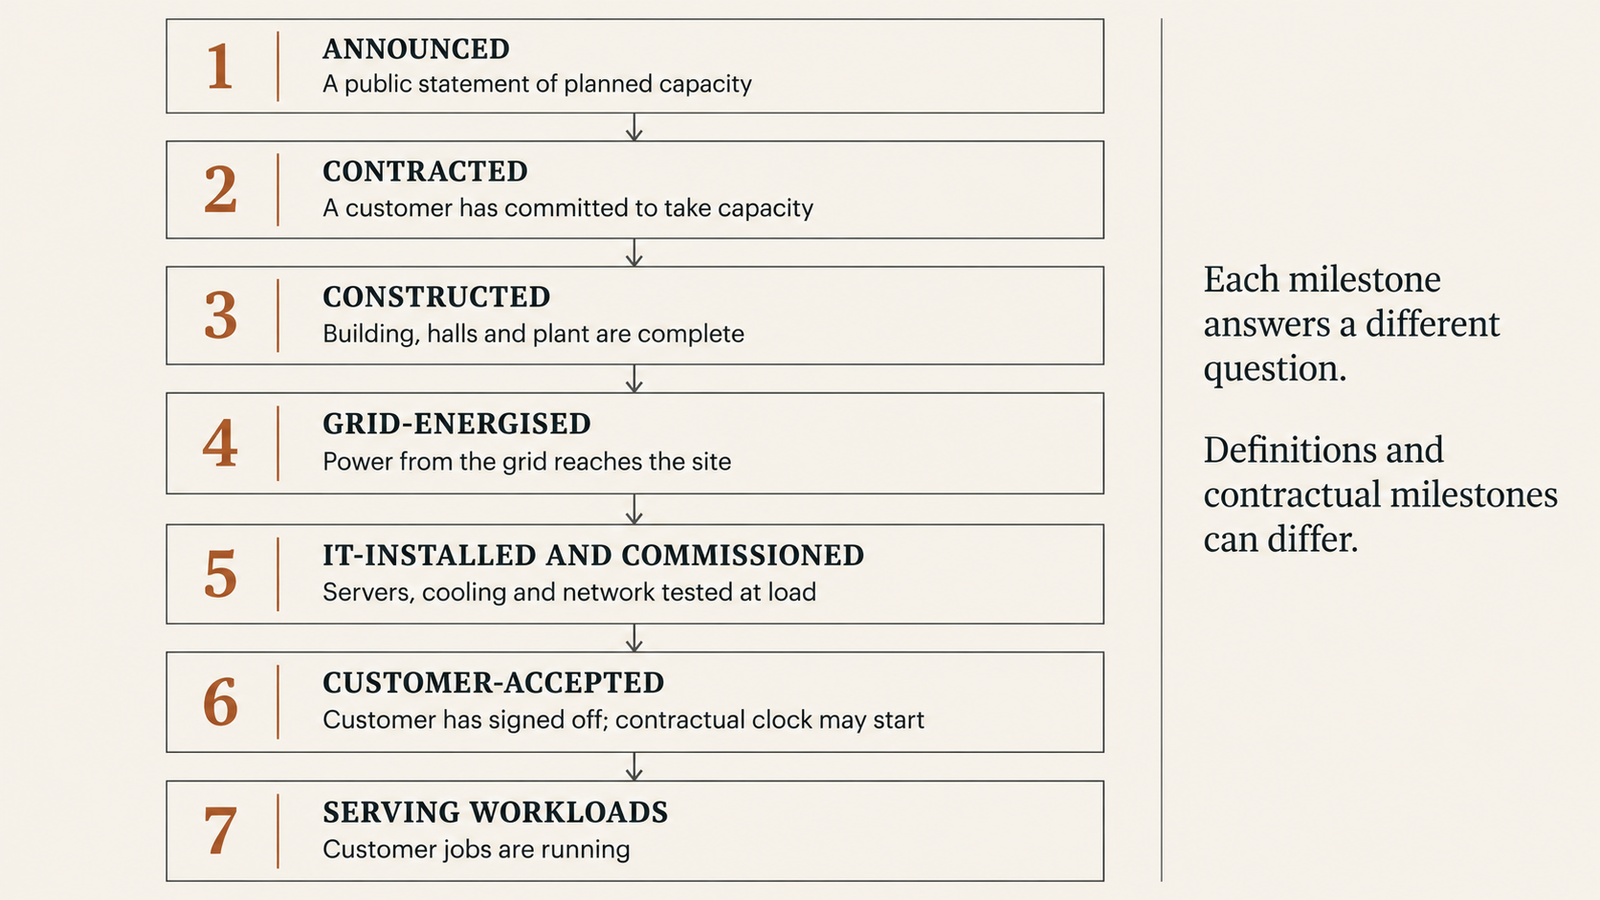
A megawatt passes through several states before it earns money, and announcements rarely say which one they mean. The seven below aren’t a universal sequence. Contracts can define delivery differently from engineering milestones, and large sites are commissioned in phases. Still, each state answers a different question.

StageWhat it meansThe question it answers
AnnouncedA public statement of planned capacityWhat does the company intend to build?
ContractedA customer has committed to take capacity on agreed termsWho has agreed to pay, and when?
ConstructedBuilding shell, halls and plant are physically completeDoes the facility exist?
EnergisedThe grid connection is live and power reaches the site’s distributionCan the site draw its rated power?
Installed and commissionedServers, accelerators, networking and cooling are installed and tested togetherCan the equipment run at load?
Customer-acceptedThe customer has signed off against contractual testsHas billing, or the contractual clock, started?
Serving workloadsCustomer jobs are runningIs the capacity doing useful work?

The gap between stages 1 and 7 is where pipelines start to look different from reality. Nscale’s filing illustrates the scale: about 25,000 GPUs active out of 461,000 classified as active or contracted. That’s not evidence of anything going wrong. Most of those contracts are for capacity that was never meant to exist yet. But a headline figure that blends all seven stages tells an investor very little about near-term revenue.

data centre capacity delivery

The physical chain behind data centre capacity delivery

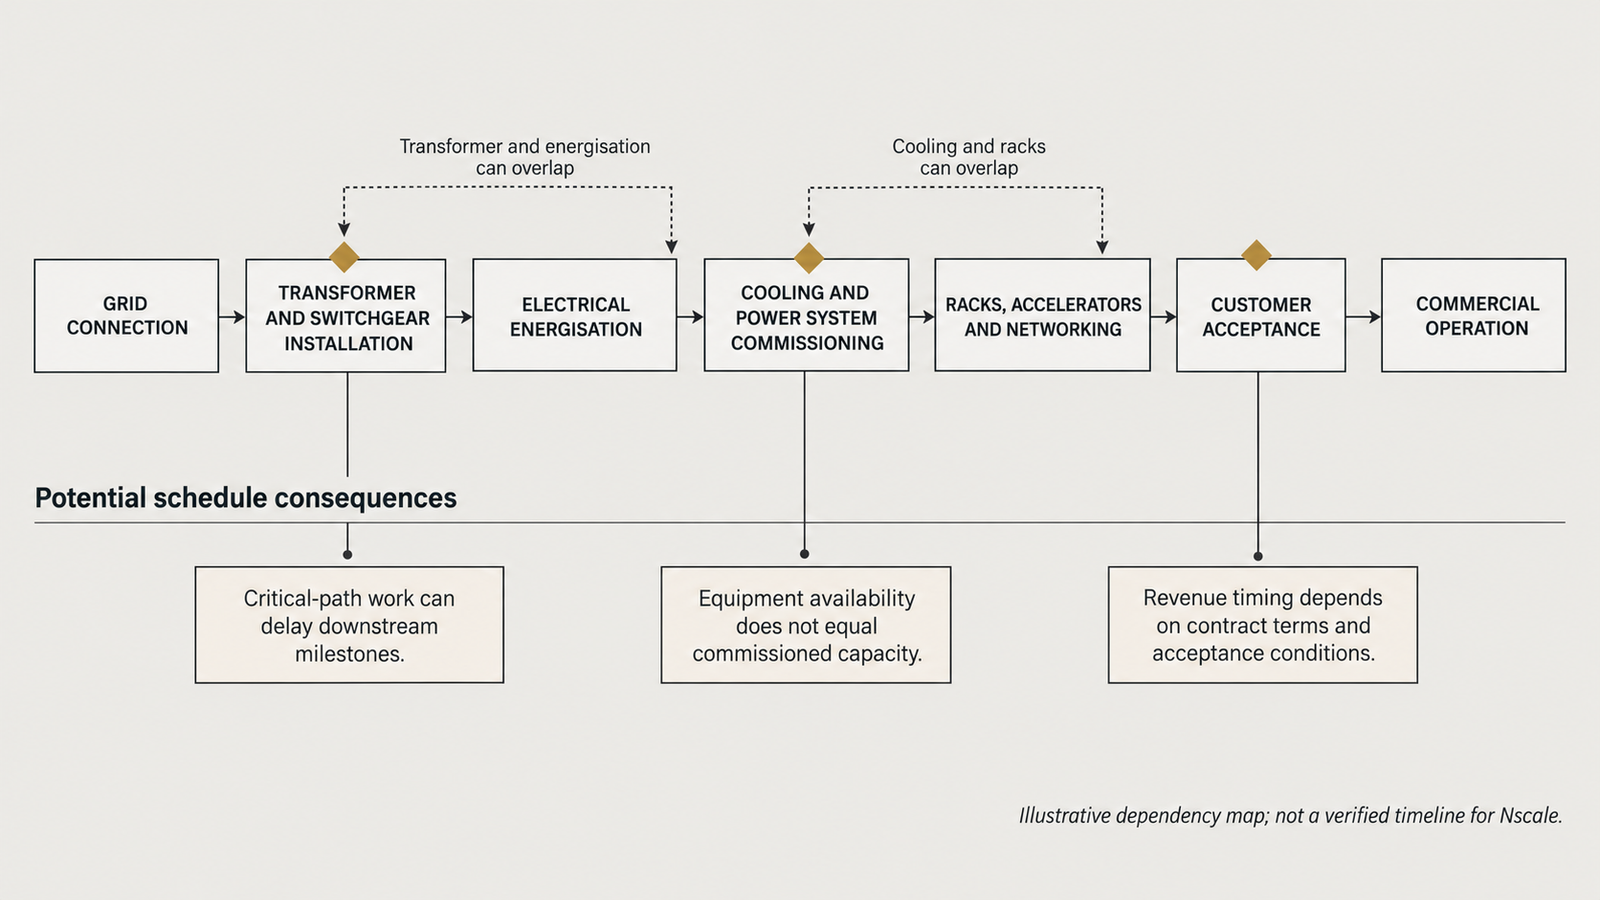
Behind every operational megawatt is a chain of dependencies, and a hold-up in one link stops everything after it. The chain runs roughly like this. A grid connection has to be agreed and the network reinforced. High-voltage transformers and switchgear have to be delivered, installed and protected. The building and its cooling and power distribution have to be finished and commissioned. Only then can racks, accelerators and network fabric be installed, tested and handed to a customer.

At Glomfjord, Bloomberg’s reporting points to problems in the middle of that chain, not at the grid connection. According to Quartz’s account, Bloomberg cited slow construction, local regulatory hurdles and coolant leaks. It also cited a fire that began in December when a transformer burned, which Bloomberg drew from public records. A Norwegian safety agency identified 10 violations at the site, and regulators closed the case in September after Nscale made fixes. DCD adds that Nscale towed in a floating hotel, the Kalmar, to house construction workers.

That list establishes what went wrong at this site. It doesn’t establish how much each problem contributed to the six months. A transformer fire is a specific event. That doesn’t make it a sign of the industry-wide transformer shortage that often features in reporting on data centre delays, and nothing in the public record links Glomfjord’s delay to equipment lead times or grid capacity. Likewise, coolant leaks in a liquid-cooled hall are a commissioning failure. They aren’t evidence that liquid cooling is unworkable.

The last stage of the chain is the least visible. A hall can be energised and cooled with its GPUs on site and still not serve a customer. Racks need integrating, the network fabric has to be built and tested, firmware and drivers have to be aligned, and the customer’s acceptance tests have to pass. Even then, the hardware has to be kept busy. As our analysis of why accelerator utilisation decides the cost of every token argued, idle accelerators still have to be paid for. A commissioned megawatt with low utilisation costs much the same and earns far less.

data centre capacity delivery

The Arctic trade-off at Glomfjord

The case for building near the Arctic Circle is real but specific. Nscale says the site runs on “100% renewable power generated by the region’s hydropower dams,” uses adiabatic cooling that “leverages the local climate,” and benefits from a “stable oversupply” of renewable power. These are the company’s claims. The low ambient temperatures are a matter of geography. The power claims haven’t been independently tested in public, and the grid-oversupply claim comes with no figures.

The costs are specific too. Nscale’s own site page describes Glomfjord as “a small industrial town of 1000 people.” A town that size has limited local workforce, accommodation and contractor capacity for a fast build, which is consistent with the reported need to bring in a floating hotel for workers. Specialist equipment and replacement parts have to travel further, and replacing a failed transformer can take longer far from major suppliers. None of this proves that the location caused the delay. It does mean that the conditions that make Glomfjord efficient to run are different from the ones that make it fast to build.

The general lesson is narrower than “Nordic sites are slow.” Cheap, clean power and cold air reduce operating costs once a site is running. They do little to speed up construction, and they can’t make a remote site easier to staff. A buyer comparing sites needs both numbers: the operating cost per megawatt and the date by which that megawatt will be delivered.

Stress-testing the revenue timeline

A delay doesn’t just postpone revenue. It changes when each cash flow happens, and those changes don’t move in step.

Four events are often treated as one: accounting revenue recognition, contractual payment obligations, cash collection, and actual workload consumption. Under many capacity contracts, the customer’s obligation starts at acceptance, not at energisation. Revenue is then recognised as capacity is made available, cash arrives on the invoice terms, and the customer’s workloads may ramp up more slowly than either. Nscale’s Glomfjord contract terms aren’t public, so it’s unknown which of these the delay pushed back, or by how much.

What the filing does disclose is that the risk runs both ways. Nscale says its contracts include delivery milestones, service-level requirements and penalties for delay. Anthropic may terminate a tranche without liability if Nscale fails to deliver it within a specified period after the expected delivery date. Bloomberg reported, through people familiar with the matter, that Glomfjord’s delays left Nscale liable for penalties totalling millions of dollars. Customers were reportedly offered better terms on new contracts instead of collecting them. That’s a quieter cost, but a real one. It shows up as lower future margins, not as a one-off charge.

Here’s an illustrative calculation. It isn’t Nscale’s data. Suppose a provider spends $1 billion building and equipping a hall that is expected to bill $20 million a month from acceptance. A six-month delay defers $120 million of billings, but the capital is already spent and financing costs keep running. At an 8% annual cost of debt on the full $1 billion, six months of interest is about $40 million. That’s money paid with nothing coming in, before any penalties or concessions. The figures are hypothetical. The mechanism isn’t. Capex goes out on the construction timeline, and income arrives on the acceptance timeline.

That mechanism is why delivery risk reaches the balance sheet. Our analysis of how lenders repriced CoreWeave’s AI infrastructure debt found the same gap at a much larger scale. CoreWeave’s $103.7 billion of remaining performance obligations depended on capacity that hadn’t yet been built, while its debt payments were already scheduled. Nscale’s $103.4 billion contract figure is a different measure from CoreWeave’s RPO, but the same question applies to both: how much of it can be delivered before the bills come due?

Reading a capacity pipeline before an IPO

Pipeline figures are hard to compare because they measure different things, and press releases rarely say which. Three recent examples show the range.

Google’s 6 October agreements with Constellation, reported as 3.59 GW, are electricity supply: an 890 MW, 20-year nuclear-uprate power purchase agreement and a 2,700 MW, 15-year supply deal. That’s power secured, not data-centre capacity built. Alibaba’s 20 GW is a stated target for Alibaba Cloud’s data-centre capacity by 2032. It’s stage 1 in the audit above. Nscale’s $103.4 billion is contracted value, measured in dollars rather than megawatts. Adding or ranking these figures against each other would produce a meaningless number.

The same caution applies to compute commitments. As we found in our analysis of the obligation behind Anthropic’s $518 billion compute commitment, a commitment from the buyer’s side depends on capacity that providers like Nscale still have to deliver. A delay at the supplier becomes a timing problem for the buyer.

For anyone reading a prospectus, a short set of questions separates pipeline from production:

  • Which measure? IT load, facility power or grid connection, and is it stated as nameplate or delivered?
  • Which stage? Contracted, energised, commissioned, accepted or serving workloads. How much is at each stage today?
  • When does the money start? At delivery, acceptance or consumption, and what penalties or termination rights apply if the date slips?
  • What’s the conversion record? How have previous sites performed against their announced dates and capacities?
  • Who carries the gap? Is construction financing committed, or does it depend on a capital raise that a delay could make harder?

The last point applies here. Nscale’s filing says it had no binding financing commitments for the Anthropic agreements, which are its largest. That doesn’t mean it can’t get financing. It does mean the delivery timeline and the financing timeline depend on each other.

What data centre capacity delivery reporting should look like

The Glomfjord reports don’t show that Nscale’s business model is broken. A delay of six months at one site, with fires, leaks and inspections along the way, is the kind of thing that happens on complex industrial projects, and a delay isn’t a failure. What the episode shows is how little a single headline megawatt figure tells you. The same campus is “30 MW operational” on the company’s website and 6.4 MW running in Bloomberg’s reporting, and readers can’t tell which figure describes what.

A better standard would be simple: report capacity at each milestone, define the unit used, and give the date. Announced, energised, commissioned, accepted and serving workloads are five different facts. A company preparing to list at a reported valuation of up to $35 billion is better served by publishing all five than by asking investors to trust one. Until the industry reports data centre capacity delivery that way, the gap between announced and delivered megawatts will keep turning up in places like Glomfjord, and readers will find out about it from news reports rather than from the companies.

FAQ

What is the difference between announced and operational data centre capacity?

Announced capacity is what a company plans or has publicly committed to build. Operational capacity is what is energised, commissioned and running workloads. Between the two are construction, grid connection, equipment installation and customer acceptance, and any of them can slip.

Why are data centre projects delayed after they’re announced?

Common causes include grid connection and network reinforcement, delivery and installation of transformers and switchgear, construction and permitting, cooling and power commissioning, and integrating servers and networks. At Glomfjord, Bloomberg reported slow construction, regulation, coolant leaks and a transformer fire. It didn’t say how much each contributed.

How does grid energisation differ from commissioning?

Energisation means the grid connection is live and power can reach the site. Commissioning means the site’s cooling, electrical systems and IT equipment have been tested together at load. A site can be energised long before it is commissioned.

What does a delayed data centre mean for revenue?

It usually defers billing, which often starts at customer acceptance, while construction and financing costs continue. It can also trigger penalties or contract concessions. The exact effect depends on contract terms, which are rarely public.

How should investors read a contracted capacity pipeline?

Ask what unit each figure uses, which milestone it has reached, when payments start, what happens if delivery slips, and how the company’s past sites performed against their announced schedules. Nscale’s filing shows $2.6 billion active out of $103.4 billion contracted, a ratio worth asking about.


Keep reading

AGI vs superintelligence

AGI vs Superintelligence: A New Name Isn’t a New Intelligence

Facts checked against official documents and reporting on 18 November 2026. On 29 September, the White House told federal agencies to stop writing “artificial intelligence” …
AI Coding Agent

AI Coding Agents Are Getting Expensive. Who’s Paying for the Tokens?

Pricing checked on official vendor pages on 17 November 2026. All USD. Cost scenarios are illustrative and labelled as such. On 28 October, TechCrunch published …
Model Weights

Verify Model Weights: 7 Checks Before You Download
Checked against the burner22/numbat repository and its discussions, Hugging Face and PyTorch documentation, and Moonshot AI’s announcement on 2 November 2026. On 1 November, a …
Agentic AI Statistics

30 Agentic AI Statistics for 2026: Adoption, Spending and Risk

Last updated: 15 November 2026. This page is updated monthly; each figure keeps its original publication date. Agent traffic at one healthcare booking platform rose …

Anthropic’s $518B Compute Commitment: The Obligation Behind It

Anthropic compute commitments

The number everyone repeated last week was $518 billion. The number that actually matters is 80%.

That is the share of Anthropic’s future compute and infrastructure commitments described as non-cancelable or payable regardless of usage, according to a confidential IPO prospectus reviewed by Reuters. Strip out the second number and the first is just a large purchase order from a company that needs a lot of chips. Keep it, and the commitment changes category: from a plan to spend into an obligation to pay.

Those are different things, and the difference is the whole story.

Having access to compute solves what has been the binding constraint on frontier AI development for three years. Being contractually obligated to pay for compute, on a schedule set in advance, converts a supply problem into a utilisation problem — and utilisation is something a company controls only partly, because it depends on customers showing up on the timetable the contracts assumed.

Key takeaways
  • A confidential IPO prospectus reviewed by Reuters shows Anthropic committed to at least $518 billion over roughly a decade across six infrastructure partners, with about 80% non-cancelable or payable regardless of usage.
  • The largest reported components: approximately $161.2bn in Broadcom-related equipment leases, $111.1bn with Google, $110bn with Amazon, $31.4bn with Microsoft, about $84.5bn for Nvidia-based capacity and about $20bn with AMD.
  • The commitments are not uniform. Reporting describes shortfall payments for Google and Amazon, cancellation only on uncured material breach for Microsoft, and leases cancelable only on default for Broadcom. One percentage covers four different contract types.
  • Anthropic spent $7.33 billion on compute and infrastructure in 2025 — more than half of $12.65 billion in total operating expenses — against revenue of $4.59 billion and $20.28 billion of cash and short-term investments.
  • Broadcom has reportedly agreed to lend up to $42 billion through a convertible note that could fund about a third of a five-year, $125.2 billion TPU lease, making one company supplier, lessor and lender at once.
  • Long-term commitments buy capacity certainty in a market where capacity has been the constraint. The cost of that certainty is financial rigidity if demand arrives later or smaller than contracted.
  • The exact terms remain unverifiable while the prospectus is confidential. That uncertainty is part of the story, not a gap in it.

Quick Navigation


What the $518 Billion Actually Represents

Anthropic’s compute commitments are contractual obligations to buy cloud services, computing capacity and AI infrastructure from named partners over a defined period. They are not a debt balance, not a cash payment, and not a single contract.

The reported breakdown, all from the prospectus as described by Reuters:

PartnerReported amountWhat it coversPeriod
Broadcom~$161.2bnEquipment lease obligations, largely non-cancelableIncludes a five-year TPU capacity lease of $125.2bn
Google~$111.1bnInfrastructure servicesApril 2026 – July 2033
Amazon$110bnInfrastructure servicesMay 2026 – April 2036
Nvidia-based capacity~$84.5bnCompute capacityThrough 2029
Microsoft$31.4bnInfrastructure servicesNovember 2026 – May 2033
AMD~$20bnAI computeNot reported

Those six figures sum to roughly $518 billion, which matches the headline. Note the composition: the single largest line is not a cloud contract at all but equipment leases, which behave differently from service agreements in both accounting and cancellation terms.

Three distinctions matter before anyone compares this to a balance sheet.

  1. Commitment is not cash. A ten-year obligation is paid over ten years. Spread evenly — which it will not be, since these ramp — $518 billion is roughly $50 billion a year, against the $7.33 billion Anthropic actually spent on compute and infrastructure in 2025.
  2. Commitment is not debt. It does not sit on the balance sheet as borrowing, though lease obligations are capitalised under current accounting. It is a future purchase obligation, disclosed in the commitments note rather than counted as leverage.
  3. The period is long and the ramp is steep. Contracts running to 2033, 2036 and beyond assume a company much larger than today’s. Reuters reported an annualised revenue run rate above $65 billion by the end of July and earlier reporting put Anthropic’s own 2028 revenue projection at roughly $190–200 billion. Those projections are the company’s, not forecasts anyone has validated.

The useful comparison is not $518 billion against $4.59 billion of 2025 revenue — that ratio is dramatic and tells you almost nothing. It is annual contracted spend against annual revenue in each future year, which is where the question of whether the commitments are comfortable or binding actually gets settled.

The Obligation Hidden Inside the Headline

The 80% figure is a summary statistic covering several different contractual mechanisms, and the mechanisms matter more than the average.

From the reporting:

  • Google and Amazon: Anthropic must pay the difference if its actual spending falls short of the minimum commitment. This is a shortfall provision — you can buy less, but you pay the same.
  • Microsoft: the agreement is described as non-cancelable through May 2033 absent an uncured material breach.
  • Broadcom: the equipment leases are largely non-cancelable except after default, and certain payment or performance defaults could make a substantial portion of the lease obligations immediately payable.
  • The Nvidia-based capacity arrangement: described as giving Anthropic more room to retreat than the others.

So “80% non-cancelable” bundles a minimum-volume commitment, a breach-only termination clause, a lease default provision and at least one more flexible arrangement under a single number.

That distinction has a practical consequence. A shortfall provision caps your downside at the committed spend — you lose the optionality, not more. A lease acceleration clause is different in kind: default can pull future payments forward into the present, which turns a long-dated obligation into an immediate one at exactly the moment a company would least be able to meet it.

The prospectus itself flags this. Reporting describes a warning that certain defaults could accelerate a substantial portion of lease obligations while also restricting Anthropic’s ability to draw on the $42 billion Broadcom facility to cover them. A financing facility that becomes unavailable precisely when it is needed is a standard credit structure and a real risk factor.

What cannot be verified: the actual contract language, the ramp schedules, the definitions of “minimum commitment”, any price-adjustment or technology-refresh provisions, and whether the agreements contain renegotiation mechanisms that reporting has not described. The prospectus remains confidential. Anyone asserting precision about these terms is working from the same journalism everyone else is.

Take-or-Pay Changes the Utilisation Equation

Take-or-pay means the buyer pays for a contracted quantity whether or not it takes delivery. The structure comes from energy and shipping, where suppliers build expensive dedicated capacity and need revenue certainty to justify it. It is appearing in AI infrastructure for exactly the same reason: someone has to fund the data centre before the demand shows up.

For the buyer, take-or-pay converts a variable cost into a fixed one. That is the entire economic consequence, and it cuts both ways.

Anthropic compute commitments

Here is what it does to the unit economics. The following is a hypothetical illustration, not a description of any Anthropic contract or price.

Suppose a company commits to $10 billion of compute capacity for a year under a take-or-pay arrangement.

ScenarioCapacity usedCost incurredEffective cost per unit used
Demand as planned100%$10bn1.0x
Demand arrives late70%$10bn1.43x
Demand disappoints50%$10bn2.0x
Usage-based contract, same shortfall50%$5bn1.0x

Under a usage-based contract, a demand shortfall is a revenue problem. Under take-or-pay, the same shortfall is a revenue problem and a margin problem, because the denominator shrinks while the numerator does not.

This is why utilisation stops being an engineering concern and becomes a financial one. When capacity is elastic, running accelerators at 60% is an optimisation question — you are leaving efficiency on the table. When capacity is committed and paid for regardless, 60% utilisation means 40% of a contracted dollar produced nothing, and that gap flows directly into gross margin. We worked through the mechanics of where idle capacity comes from in our analysis of accelerator utilisation, and every source of idle time in that piece becomes more expensive under this contract structure.

The pressure this creates is directional and predictable. A company with committed capacity has strong incentives to fill it: push inference volume, expand enterprise contracts, launch workloads that consume compute, price aggressively to drive usage. None of those are irrational responses. They are what the contract structure rewards.

The honest caveat: none of this establishes that Anthropic is underutilising anything. Its reported run-rate growth suggests demand has been the easier half of the equation so far. The point is structural — take-or-pay raises the cost of being wrong about timing, for anyone who signs it.

Why Compute Certainty Can Be Worth Paying For

It would be easy to write this as a cautionary tale. That reading ignores why a competent management team signs these contracts, and the reasons are good ones.

For the past three years, the binding constraint on frontier AI has been access to compute, not demand for it. Accelerators have been allocated rather than sold. Memory has been contracted years ahead. Data-centre power has become a multi-year procurement problem. In that environment, a company without secured capacity does not get to choose how fast it grows.

What a long-term commitment buys:

  • Capacity that exists. Suppliers build against contracted demand. An uncommitted buyer competes for whatever is left.
  • Price certainty in a rising market. If compute costs rise, a fixed contract becomes an asset. The hedge runs both directions.
  • Planning horizon. Model development schedules depend on knowing what hardware will be available and when.
  • Priority on new generations. Being a large committed customer affects allocation when the next accelerator ships short.
  • Scale economics. Volume commitments buy better unit pricing than spot purchasing.

There is also a competitive dimension. If frontier capability tracks compute, then capacity secured is capability secured, and capacity your competitor cannot buy is capability they cannot build. Commitments of this size take supply off the market.

The trade-off is clean enough to state in one sentence: Anthropic has exchanged financial flexibility for compute certainty. Whether that was a good trade depends entirely on which constraint turns out to bind — and that will not be clear for years.

The Partners Behind the Anthropic Compute Commitments

The prospectus, as reported, identifies Amazon, Google and Microsoft as simultaneously investors, customers, cloud providers, distributors and competitors. That is not a conflict the company is hiding; it is one it is disclosing as a risk.

Each role pulls differently. As an investor, a partner benefits from Anthropic’s success. As a supplier, it benefits from Anthropic’s spending. As a distributor, it takes a margin on Anthropic’s models. As a competitor, it builds models that compete with them. The same counterparty occupies all four positions at once.

The Broadcom structure is the sharpest version. Reuters reported on October 1 that Broadcom agreed to lend Anthropic up to $42 billion through a convertible note that could fund roughly a third of the five-year, $125.2 billion TPU compute lease, with Broadcom permitted to designate a financing partner and the debt convertible into Anthropic equity. Anthropic is expected to become the largest customer in Broadcom’s chip design business next year.

So one company supplies the hardware, leases it, lends the money to pay for the lease, and may end up holding equity. The prospectus reportedly flags potential conflicts of interest directly, warning that Broadcom’s decisions on pricing and hardware could affect Anthropic’s ability to procure enough computing infrastructure.

Broadcom’s own public filings describe a structure of this shape without naming a customer. Its 10-Q for the quarter ended August 2, 2026 discloses an “AI XPV platform” launched in June 2026 with an initial $35 billion tranche led by a financial partner, enabling deployment of more than a gigawatt of compute infrastructure for a customer, with Broadcom providing a backstop on that customer’s five-year lease obligations and maximum potential liability of roughly $29 billion. Broadcom does not identify the customer, and no public source establishes that these are the same arrangement.

The economic observation, offered as analysis: vendor financing linked to future demand for the vendor’s own product is not new — it is how equipment vendors have supported large customers for decades, and Nvidia has done versions of it recently. What is different here is the concentration. The same relationship carries supply risk, credit risk and equity exposure, and a stress event in one leg propagates to the others. Rothschild’s Robert Leitao put the market’s version of this concern plainly, questioning whether the revenue base can keep pace with the scale of financing that has been arranged.

Leases, Depreciation and the Technology Risk in a Long Contract

Three concepts get conflated whenever AI infrastructure costs come up, and they are related but not interchangeable.

ConceptWhat it isWhere it shows up
Contractual commitmentA promise to buy capacity or services in future periodsCommitments note; lease liabilities on the balance sheet
DepreciationAllocation of an owned asset’s cost across its useful lifeOperating expenses, for hardware you own
Operating expenseCash cost of running the business in a periodIncome statement

For a company leasing capacity rather than buying accelerators, depreciation largely sits with whoever owns the hardware — but the economics do not disappear. They arrive embedded in the lease rate, because the lessor priced in the asset’s expected useful life when setting it.

That is where the technology risk lives. A five-year lease on a specific accelerator generation assumes that generation stays economically competitive for five years. Hardware improves on a roughly annual cadence now, and what ends an accelerator’s economic life is usually not failure but the arrival of something that does more per watt and holds more memory — the pattern we examined in our piece on AI accelerator depreciation.

Follow that through. If performance per dollar improves sharply in 2029, a lease signed in 2027 at 2027 rates becomes expensive relative to what the market then offers. The capacity still works. It is simply worth less than it costs, and the contract does not care.

This is the structural reason long compute contracts carry risk that long property leases do not. A building is still a building in year seven. An accelerator generation may be two or three generations behind by then, and the memory capacity that made it viable for a given model size may no longer fit the models being served.

The counterweight, in fairness: the TPU capacity in question reportedly starts coming online in 2027 and the lease runs five years from there, which is roughly in line with how hyperscalers depreciate their own fleets. These are not exotic terms. They are standard terms applied at an unusual scale, and the scale is what makes the technology-refresh assumption consequential.

What Could Make the Anthropic Compute Commitments Work

The bull case is not complicated, and it is mostly about one variable arriving on schedule.

If enterprise AI demand grows as projected, contracted capacity gets consumed, and the commitments look like foresight rather than exposure. Reuters reported an annualised revenue run rate above $65 billion by the end of July, against $4.59 billion for full-year 2025. A company growing at that rate does not have a utilisation problem; it has a capacity problem, which is what the contracts solve.

Several things reinforce that outcome:

  • Compute stays scarce. If accelerators, memory and power remain constrained, fixed-price contracts signed earlier look cheap later.
  • Agentic and reasoning workloads consume more per task. Demand per customer rises without needing more customers.
  • Enterprise contracts lengthen. Multi-year customer commitments on the revenue side offset multi-year obligations on the cost side, which is the natural hedge.
  • Scale lowers unit cost. Large committed volumes buy better pricing than anyone purchasing on demand.

The cleanest version of the bull case: the commitments convert an unpredictable supply risk into a predictable cost, in a business where supply has been the thing that limited growth.

What Could Make Them Expensive

The bear case does not require AI demand to collapse. It only requires the economics of compute to move faster than the contracts.

  • Efficiency improves faster than demand grows. Better quantisation, more efficient architectures and cheaper serving reduce compute per unit of output. The same revenue then needs less capacity, and contracted capacity goes unused.
  • Performance per dollar jumps. A new accelerator generation that is substantially more efficient makes older contracted capacity expensive relative to what is available, exactly as described above.
  • Price competition compresses margins. If model API prices keep falling — and they have fallen steeply — revenue per unit of compute falls with them, while the cost per unit is fixed by contract.
  • Demand arrives late rather than never. This is the underrated scenario. Contracts ramp on a schedule. If adoption lands two years behind the schedule, the capacity is paid for during the gap.
  • Customer concentration bites. Reporting indicates two customers supplied nearly a quarter of 2025 revenue. Concentrated revenue against distributed fixed obligations is an asymmetry worth noting.
  • Capital markets tighten. Much of this structure assumes continued access to financing, including the Broadcom facility. The prospectus reportedly warns that certain defaults could both accelerate lease obligations and restrict access to that facility.

None of these is a prediction. They are the variables that would determine whether a commitment of this size reads as strategic or as overextended, and they are the ones worth tracking.

The Valuation Connection

A valuation above $2 trillion — against a self-estimated $965 billion in May — is a statement about future cash flows. Those cash flows depend on revenue growth, gross margin, capital intensity and how much compute each dollar of revenue requires.

What the $518 billion does is make one of those variables visible. Infrastructure spending is normally a forecast assumption that investors argue about. Here, a large portion of it is contracted, dated and disclosed. The spending is no longer a question mark; what remains uncertain is the revenue that has to arrive alongside it.

This is not an argument that the valuation is right or wrong, and this article offers no view on that. The structural observation is narrower: when costs are contractually fixed and revenues are not, the equity absorbs the variance. That is true of any capital-intensive business, and it is unusual to see it at this scale in a company five years old.

The 2025 figures give a sense of the starting point. Revenue of $4.59 billion, operating loss of $8.06 billion, compute and infrastructure spending of $7.33 billion within $12.65 billion of total operating expenses, and $20.28 billion of cash and short-term investments at year end. The headline $42 billion net loss is mostly a non-cash charge of roughly $34 billion tied to the rising estimated value of convertible financing instruments — a number that grows precisely because the company’s valuation grew, and which tells you nothing about operations.

A Note on Governance

Briefly, because it is a separate question from the economics.

Reporting describes a newly created “Founder LLC” comprising Anthropic’s seven co-founders, holding a single Class F share carrying 50.1% of voting power on certain matters including some director elections. The founders direct that share by majority vote. The structure is not permanent: a founder who leaves, dies, sells below a threshold or is removed for cause drops out, and the super-voting class begins to sunset once few enough founders remain.

That is the factual position. Dual-class structures are common in technology listings, and whether this one is appropriate is a judgement for investors rather than for this article. The relevant connection to the rest of the piece is simply that financial scale and governance structure are independent: the commitments would have the same economics under any voting arrangement.

What AI Infrastructure Buyers Should Take From This

Most organisations will never sign a contract with nine zeros. The structural lessons scale down anyway.

  • Know which of your compute spend is committed. Reserved instances, savings plans, minimum commitments and capacity reservations all behave like small take-or-pay contracts. The percentage of your bill that is committed is the percentage where utilisation becomes a margin issue.
  • Model the shortfall, not just the spend. The question is not what the commitment costs. It is what it costs if you use 60% of it.
  • Match contract duration to demand visibility. A three-year commitment against six months of demand visibility is a bet, however good the discount.
  • Price the flexibility you are selling. Vendors discount committed volume because certainty is worth something to them. Work out what it is worth to you before trading it away.
  • Watch counterparty concentration. If the same vendor supplies, finances and distributes, your exposure to them is larger than any single contract suggests.
  • Treat utilisation as a financial metric. Once capacity is committed, the operations team’s efficiency work shows up in gross margin. That changes who should be in the room when it is discussed.

The question this story leaves open is a genuine one. Does committing $518 billion remove Anthropic’s biggest risk — not being able to get compute — or substitute a different one, being obligated to pay for compute whether or not demand arrives on schedule? The answer is that it does both, and which dominates depends on variables that will take years to resolve: utilisation, revenue growth, contract terms nobody outside has seen, compute prices, model efficiency and how quickly hardware generations turn over.

Anyone offering a confident verdict today is working from the same confidential document nobody has read.

FAQ

What are Anthropic’s compute commitments?

Contractual obligations to purchase cloud services, computing capacity and AI infrastructure from named partners over fixed periods. According to a confidential IPO prospectus reviewed by Reuters, they total at least $518 billion over roughly a decade across six partners.

What is the $518 billion figure?

The sum of Anthropic’s disclosed infrastructure commitments: approximately $161.2bn in Broadcom-related equipment leases, $111.1bn with Google, $110bn with Amazon, about $84.5bn for Nvidia-based capacity, $31.4bn with Microsoft and about $20bn with AMD. It is a multi-year obligation, not a current debt or a cash payment.

What does take-or-pay mean here?

That the buyer pays for contracted capacity whether or not it is used. Reuters reported that about 80% of Anthropic’s commitments are non-cancelable or payable regardless of usage, though the specific mechanisms differ by counterparty.

What happens if Anthropic does not use the contracted compute?

Based on the reported terms, it would still owe the money in most cases — through shortfall payments to Google and Amazon, or through lease obligations to Broadcom. The exact provisions cannot be verified while the prospectus stays confidential.

Why would a company commit so much compute?

Because compute availability, not demand, has been the binding constraint on frontier AI development. Long-term commitments secure capacity, lock in pricing, support planning and give priority on new hardware generations — at the cost of financial flexibility.

Who provides Anthropic’s compute?

Six partners per the reported prospectus: Broadcom, Google, Amazon, a provider of Nvidia-based capacity, Microsoft and AMD. Amazon, Google and Microsoft are described as simultaneously investors, customers, cloud providers, distributors and competitors.

What is the Broadcom financing arrangement?

Reuters reported that Broadcom agreed to lend Anthropic up to $42 billion via a convertible note that could fund roughly a third of a five-year, $125.2 billion TPU compute lease. Broadcom may designate a financing partner, and the debt could convert into Anthropic equity.

How do compute commitments affect AI company economics?

They convert a variable cost into a fixed one. That reduces supply risk and increases operating leverage: if capacity is fully used, unit economics improve with scale; if it is not, the unused portion still has to be paid for and effective cost per unit rises.


Keep reading

AGI vs superintelligence

AGI vs Superintelligence: A New Name Isn’t a New Intelligence

Facts checked against official documents and reporting on 18 November 2026. On 29 September, the White House told federal agencies to stop writing “artificial intelligence” …
AI Coding Agent

AI Coding Agents Are Getting Expensive. Who’s Paying for the Tokens?

Pricing checked on official vendor pages on 17 November 2026. All USD. Cost scenarios are illustrative and labelled as such. On 28 October, TechCrunch published …
Model Weights

Verify Model Weights: 7 Checks Before You Download
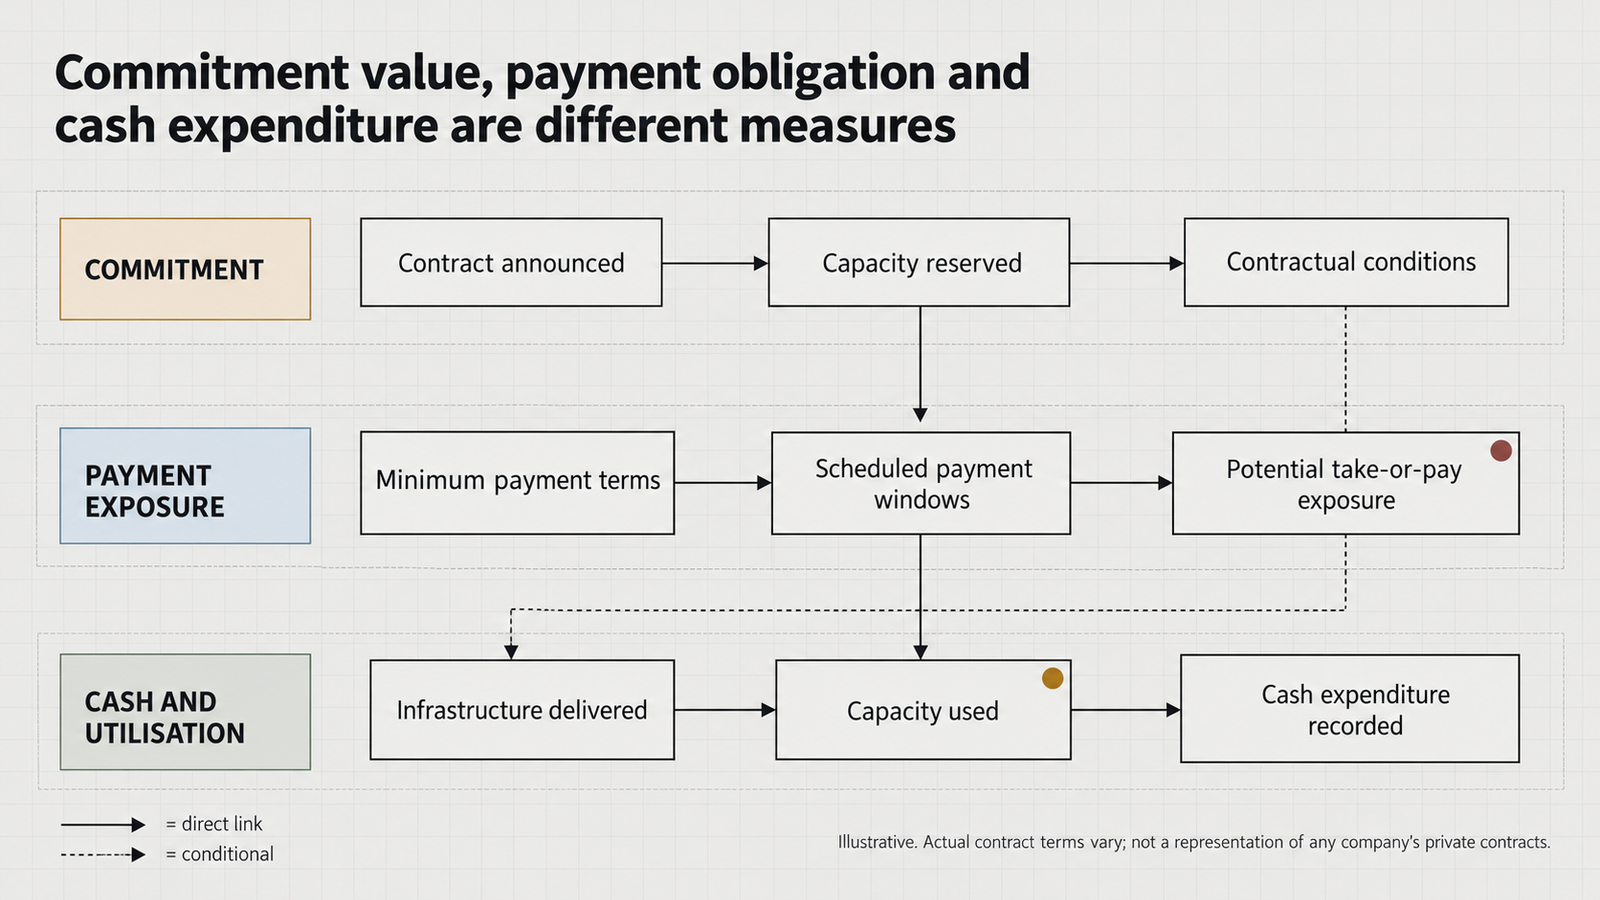
Checked against the burner22/numbat repository and its discussions, Hugging Face and PyTorch documentation, and Moonshot AI’s announcement on 2 November 2026. On 1 November, a …
Agentic AI Statistics

30 Agentic AI Statistics for 2026: Adoption, Spending and Risk

Last updated: 15 November 2026. This page is updated monthly; each figure keeps its original publication date. Agent traffic at one healthcare booking platform rose …